A visit from GST officers for inspection or search can feel stressful, but the law sets out clear procedures, and knowing them helps a business respond calmly and correctly. GST search and seizure powers under section 67 of the CGST Act are meant to be used on a proper authorisation and in a structured way, with safeguards for the taxpayer.
This article explains what inspection, search and seizure mean, the documents you should see, your rights and responsibilities during the process, and what typically follows. It is written to help owners and finance teams stay prepared, not alarmed.
Key takeaways
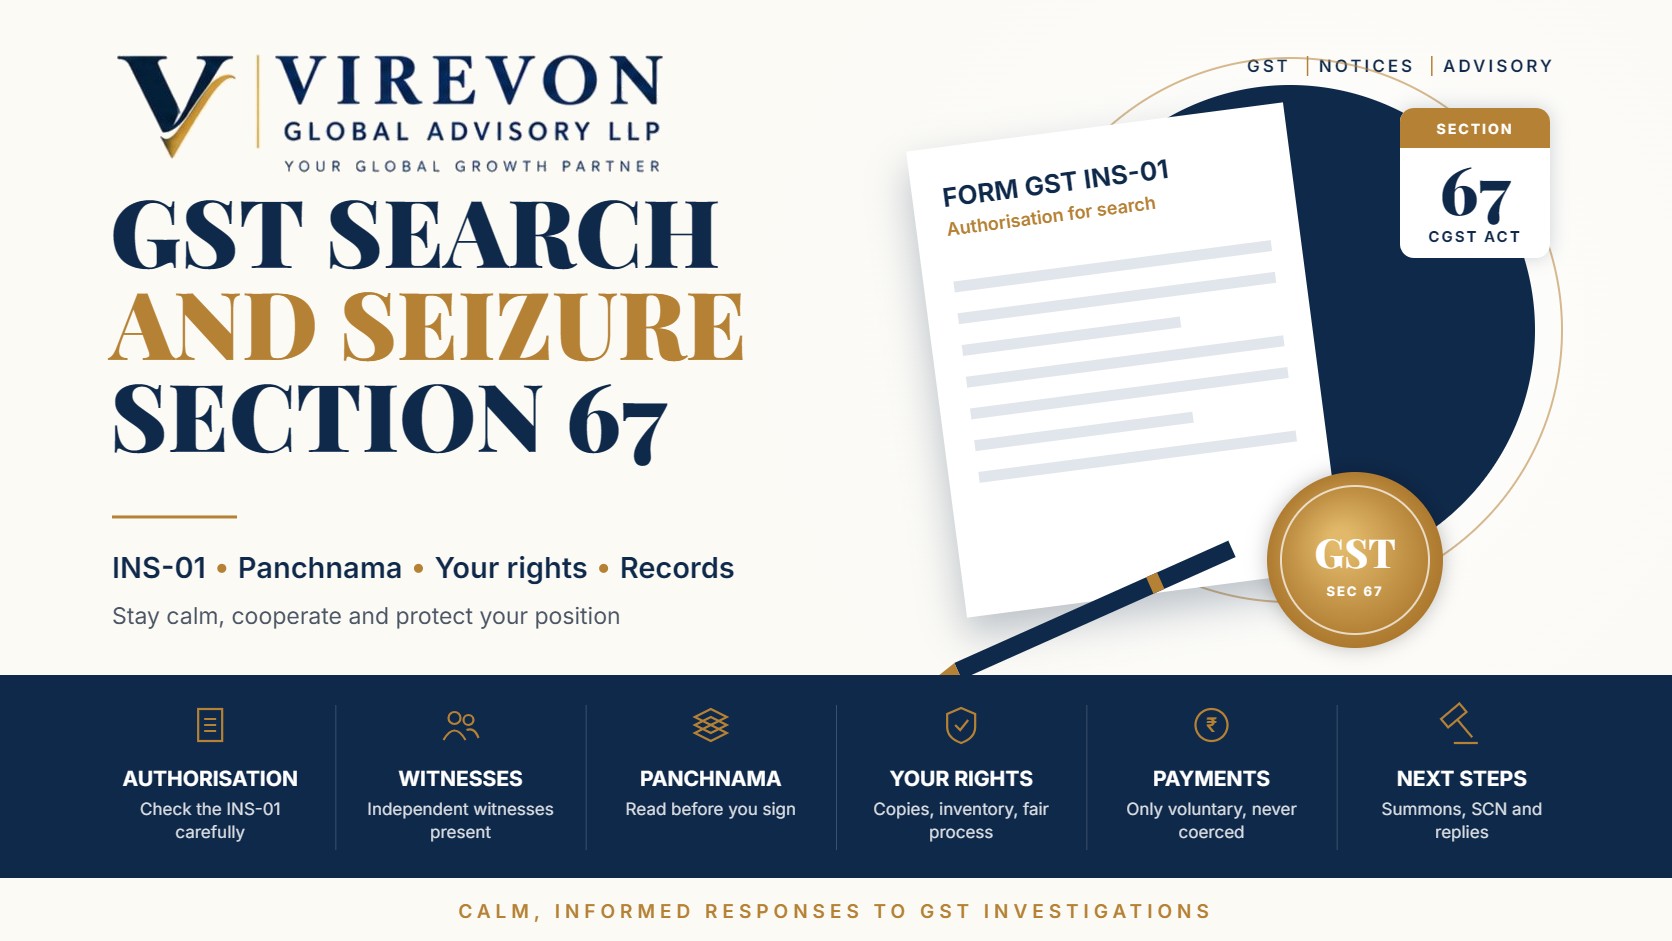
- Section 67 allows inspection, search and seizure only on written authorisation by an officer of the rank of Joint Commissioner or above, based on “reasons to believe”.
- Authorisation for inspection or search is issued in Form GST INS-01, and seizure is recorded in Form GST INS-02.
- Proceedings are recorded in a panchnama in the presence of independent witnesses; read it fully before signing.
- CBIC Instruction No. 01/2022-23 (GST-Investigation) dated 25 May 2022 states that there should be no recovery by force or coercion during search; payment is only voluntary.
- Most searches lead to follow-up summons and records requests, and any demand must go through the normal show cause process.
Inspection, search and seizure: what the terms mean
- Inspection is a less intrusive step where officers visit your premises to examine goods, books or documents.
- Search is a more detailed exercise to find goods, documents or things believed to be relevant to tax evasion or to proceedings under the Act.
- Seizure is the taking into custody of goods, documents, books or things found during search that are useful for proceedings.
Where it is not practicable to seize goods, officers may instead issue a prohibition order (Form GST INS-03), asking you not to remove or deal with them without permission.
What you should see at the start
- Identity of officers: ask to see identity cards.
- Authorisation in INS-01: check the name of the person or business, the premises covered and the signing authority.
- Independent witnesses: searches are generally conducted in the presence of two independent witnesses, as required by the procedure for searches.
If the premises in the authorisation are different from your premises, or the document is unsigned, politely point this out and note it for your records.
Your rights during GST search and seizure
| Your right | What it means in practice |
|---|---|
| To see the authorisation | Officers should show INS-01 before starting |
| To have a copy of the panchnama | You can ask for a copy of the record of proceedings |
| To an inventory of seized items | Seized goods and documents are listed in INS-02 |
| To copies of seized documents | You may take copies or extracts, except where it would prejudice the investigation |
| To have documents returned | Documents not relied upon in a notice are to be returned within 30 days of the notice |
| No coercive recovery | Tax may be paid only voluntarily, not under pressure |
| To legal advice | You can consult your advisers during and after the proceedings |
Your responsibilities
A search goes more smoothly when the business cooperates professionally:
- Provide access to the premises, records and systems covered by the authorisation.
- Do not remove, hide or destroy goods or records, including digital data.
- Give accurate information; if you do not know an answer, say so and offer to provide it later.
- Nominate one senior person to coordinate with officers and keep notes of what is examined and taken.
- Keep statements factual. Statements recorded can be used later, so they should be accurate and considered.
Seized goods and documents
Goods seized can be released provisionally on execution of a bond and security in the prescribed form, or on payment of applicable tax, interest and penalty. If no notice is issued within six months of seizure, the goods are to be returned to the person from whom they were seized, although this period can be extended by up to six months for sufficient cause.
For documents and books, officers retain them only for as long as needed for examination and proceedings. Keeping your own backup copies of key records, especially digital ones, makes business continuity easier.
Voluntary payment during search: know the position
Businesses are sometimes unsure whether to pay tax during or right after a search. The position under CBIC Instruction No. 01/2022-23 is clear: there should be no recovery by force or coercion during search, inspection or investigation. If a taxpayer chooses to pay voluntarily, it is done through Form DRC-03, and it should be a genuine, informed decision.
Before paying, consider:
- whether the liability is correctly computed;
- whether it relates to periods and issues that are genuinely payable;
- the benefit of paying early, such as lower penalty exposure in some cases.
Our guide to DRC-03 voluntary payment and DRC-03A explains how such payments are recorded and later adjusted.
What usually happens after a search
- Summons to record statements or produce documents.
- Requests for reconciliations and supporting records for the periods under review.
- Show cause notice, if the department believes tax is short paid or ITC wrongly availed, followed by a reply and personal hearing. Our guide on replying to a GST show cause notice covers that stage.
A readiness checklist for businesses
- Keep invoices, e-way bills and stock records organised and up to date.
- Reconcile books with GSTR-1, GSTR-3B and GSTR-2B monthly.
- Maintain supplier due diligence, especially for new or high-value suppliers.
- Store contracts and key correspondence centrally.
- Brief senior staff on who will coordinate if officers visit.
Frequently asked questions
Who can authorise a GST search?
Under section 67, an officer not below the rank of Joint Commissioner can authorise inspection, search and seizure in writing, in Form GST INS-01.
Do I have to sign the panchnama?
The panchnama records the proceedings. Read it carefully before signing, and ensure it correctly lists what was examined and seized. You can ask for a copy.
Can officers force me to pay tax during a search?
No. CBIC instructions state there should be no recovery by force or coercion. Any payment must be voluntary, through Form DRC-03.
Will seized goods be returned?
Goods can be released provisionally against a bond and security. If no notice is issued within six months (extendable by six months), they are to be returned.
If your business is facing a GST inspection or search, or you want to strengthen your records in advance, our GST litigation team will be glad to guide you calmly through each step.
This article is general information based on the law as of September 2026, and is not legal or tax advice. Please check the facts of your own case with a professional before acting.