One of the most frustrating GST situations for a buyer is paying the full invoice, GST included, only to find that the supplier never deposited the tax. The rules on ITC reversal supplier not paid tax situations can then require you to give up the credit, at least until the supplier complies. Two provisions matter most: section 16(2)(c) of the CGST Act and Rule 37A of the CGST Rules.
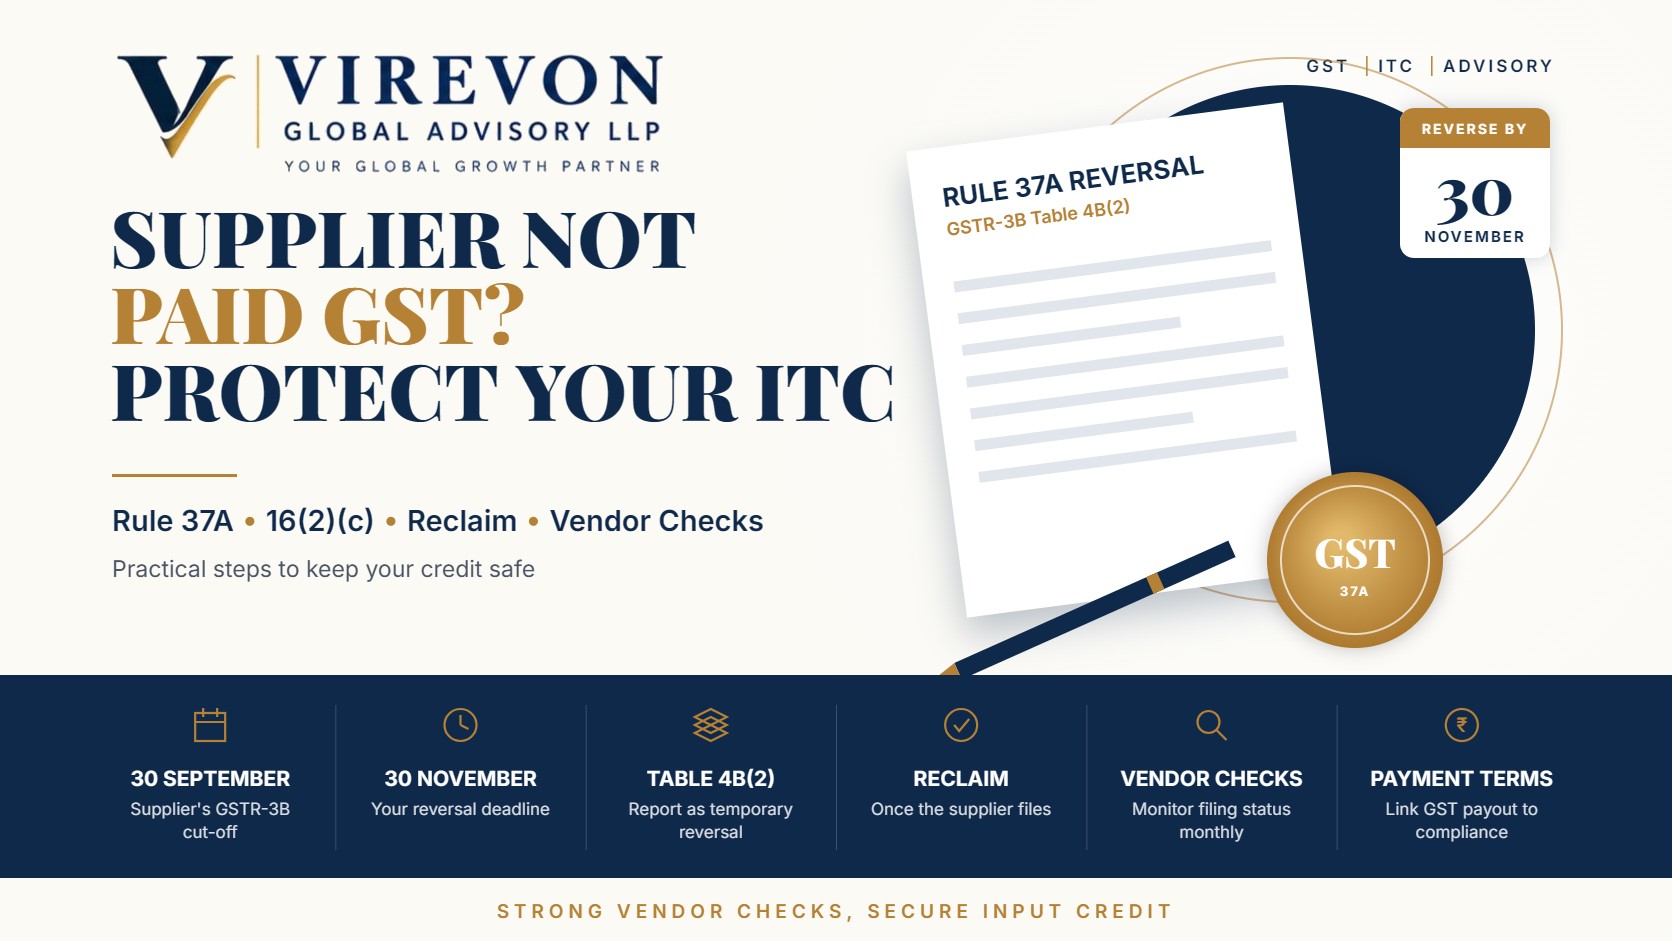
The timing is important this month. For FY 2025-26 invoices, suppliers had until 30 September 2026 to file their GSTR-3B, and buyers must reverse credit on defaulting suppliers’ invoices by 30 November 2026. This guide explains how the provisions work, how to reverse and reclaim correctly, and what practical steps protect your credit in future.
Key takeaways
- Section 16(2)(c) makes ITC conditional on the supplier actually paying the tax to the government.
- Under Rule 37A, if the supplier has not filed GSTR-3B for the period by 30 September of the following year, the buyer must reverse the related ITC by 30 November.
- For FY 2025-26, the reversal deadline is 30 November 2026; the portal flags such invoices in the September 2026 GSTR-2B.
- Report the reversal in Table 4B(2) of GSTR-3B and reclaim it through Table 4D(1) once the supplier files and pays.
- Regular vendor checks, sensible payment terms and good documentation are the best protection.
What section 16(2)(c) requires
Section 16(2) lists the conditions for claiming ITC. Clause (c) requires that the tax charged on the supply has actually been paid to the government, either in cash or through the supplier’s own admissible credit. The buyer, however, has no direct way to confirm what the supplier has paid. In practice, the department relies on the supplier’s GSTR-3B filing as the signal.
This condition has been debated before several courts, particularly for buyers who paid in full and had genuine documents. The position can depend on facts and on jurisdiction, so any demand based on a supplier’s default should be examined carefully rather than simply accepted.
How Rule 37A works
Rule 37A gives a mechanical process for supplier default:
- You availed ITC on an invoice or debit note that appeared in your GSTR-2B.
- The supplier did not file the GSTR-3B for that tax period by 30 September following the end of the financial year.
- You must reverse the ITC in a GSTR-3B filed on or before 30 November of that year.
- If you do not reverse it in time, the credit is payable with interest under section 50.
- When the supplier later files the GSTR-3B, you can reclaim the credit.
Rule 37A does not apply to reverse charge supplies, since you pay that tax yourself.
Timeline for FY 2025-26 invoices
| Date | What happens |
|---|---|
| 30 September 2026 | Last date for suppliers to file GSTR-3B for FY 2025-26 periods without triggering Rule 37A |
| 14 October 2026 | September 2026 GSTR-2B is generated, showing ITC to be reversed under Rule 37A |
| 20 October 2026 or the QRMP date | Reverse in the GSTR-3B for September 2026 or the July to September quarter |
| 30 November 2026 | Outer date for reversal without interest consequences |
| Any later date | Reclaim when the supplier files and pays |
Reporting the reversal and reclaim in GSTR-3B
- Reversal: report in Table 4B(2), which is meant for reversals that can be reclaimed later.
- Reclaim: once the supplier files, report the reclaimed amount in Table 4A(5) and also in Table 4D(1), so the portal can match it against the earlier reversal.
- Ledger: your Electronic Credit Reversal and Re-claimed Statement tracks the balance. Reclaims cannot exceed what you have reversed.
A worked example
A manufacturer bought packaging material in January 2026 for ₹5,00,000 plus GST of ₹90,000. The invoice appeared in GSTR-2B and ITC was claimed. The supplier did not file its GSTR-3B for January 2026 by 30 September 2026.
- The September 2026 GSTR-2B flags ₹90,000 under Rule 37A.
- The manufacturer reverses ₹90,000 in Table 4B(2) of its September 2026 GSTR-3B, filed on 20 October 2026.
- In February 2027, the supplier files the pending return and pays the tax with interest.
- The manufacturer reclaims ₹90,000 in its February 2027 GSTR-3B, through Tables 4A(5) and 4D(1).
Because the reversal was made before 30 November 2026, no interest arises for the buyer.
How to protect your credit
Before you buy
- Check GSTIN status and return filing history on the GST portal for new vendors.
- Collect KYC documents such as registration certificate, PAN and bank details.
- Classify vendors by risk, giving closer attention to new or irregular filers.
While you pay
- Link the GST portion of payment to compliance, for example by releasing it after the invoice appears in GSTR-2B or after the supplier’s GSTR-3B is filed.
- Add contract clauses requiring timely filing and allowing recovery of ITC lost due to supplier default, with interest.
- Pay through banking channels and keep proof of every payment.
Every month
- Reconcile GSTR-2B with your books and track suppliers whose invoices are missing. Our GSTR-2B reconciliation guide explains the process.
- Use IMS actively, keeping doubtful invoices pending rather than letting them be deemed accepted. See our IMS practical guide.
- Keep evidence of genuineness: purchase orders, delivery challans, e-way bills, transport records and stock entries.
If you receive a notice
Sometimes the department identifies a supplier’s default through data analysis and issues a notice to the buyer. Respond with facts: proof of receipt of goods or services, payment including GST, the supplier’s documents, and your own reversal or reclaim position. If the supplier has since filed and paid, show that clearly. Our guide on replying to a GST show cause notice under sections 73, 74 and 74A covers the structure of a good reply.
Frequently asked questions
Do I have to reverse ITC if my supplier has not paid GST?
Under Rule 37A, if the supplier has not filed GSTR-3B for the relevant period by 30 September following the financial year, you must reverse the ITC by 30 November of that year.
Can I claim the ITC again later?
Yes. Once the supplier files the pending GSTR-3B and pays the tax, you can reclaim the credit through Tables 4A(5) and 4D(1) of GSTR-3B.
Where do I report a Rule 37A reversal?
In Table 4B(2) of GSTR-3B, which is used for reversals that may be reclaimed later.
What if I miss the 30 November deadline?
The ITC becomes payable along with interest under section 50. It is best to reverse on time and reclaim later if the supplier complies.
If you would like help reviewing supplier compliance or reversing and reclaiming ITC correctly under Rule 37A, our team would be glad to assist.
This article is general information based on the law as of September 2026, and is not legal or tax advice. Please check the facts of your own case with a professional before acting.