Tag: Startups

  • Udyam (MSME) Registration: Benefits, Classification and How to Register

    Udyam (MSME) Registration: Benefits, Classification and How to Register

    For a small manufacturer, trader or service business, Udyam registration benefits go well beyond a certificate on the wall. Registration on the Udyam portal is what formally identifies your business as a micro, small or medium enterprise (MSME), and that status opens doors to easier credit, protection against delayed payments and preference in government procurement.

    The process is free, online and largely self-declared, using your PAN and GST data. This guide explains the current MSME classification limits, the practical benefits, how to register step by step, and the few compliance points to keep in mind after registration.

    Key takeaways

    • Udyam registration is free and is done online on the official portal using Aadhaar and PAN; no documents need to be uploaded in most cases.
    • From 1 April 2025, the MSME limits were raised: micro up to ₹2.5 crore investment and ₹10 crore turnover, small up to ₹25 crore and ₹100 crore, medium up to ₹125 crore and ₹500 crore.
    • Export turnover is excluded when computing turnover for classification.
    • Key benefits include priority sector lending, collateral-free credit support, protection against delayed payments and procurement preferences.
    • Classification is updated using income-tax and GST data, so keeping those filings accurate matters.

    MSME classification: the current limits

    Classification uses a composite test of investment in plant and machinery (or equipment) and annual turnover. A business must be within both limits to fall in a category; crossing either one moves it to the next category.

    CategoryInvestment in plant and machinery or equipmentAnnual turnover
    MicroUp to ₹2.5 croreUp to ₹10 crore
    SmallUp to ₹25 croreUp to ₹100 crore
    MediumUp to ₹125 croreUp to ₹500 crore

    These limits were notified by the Ministry of MSME and apply from 1 April 2025. Investment is taken from the written-down value in the income-tax return, excluding land, building and certain specified items, while turnover is linked to GST and income-tax data for all businesses under the same PAN, with exports left out.

    An example

    A packaging unit has plant and machinery of ₹3 crore and domestic turnover of ₹14 crore, plus exports of ₹6 crore. Exports are excluded, so turnover for classification is ₹14 crore. Because investment exceeds ₹2.5 crore and turnover exceeds ₹10 crore, the unit is a small enterprise, not micro.

    The main Udyam registration benefits

    The benefits come from the MSMED Act, RBI guidelines and various central and state schemes. The most useful in practice are listed below.

    Access to finance

    • Priority sector lending: bank loans to MSMEs are counted towards priority sector targets, which encourages lenders to extend credit.
    • Collateral-free credit support: guarantee schemes such as those run through CGTMSE help eligible micro and small units borrow without third-party collateral.
    • Scheme eligibility: many subsidy, interest subvention and technology upgrade schemes require a Udyam number.

    Protection against delayed payments

    Under the MSMED Act, buyers must pay registered micro and small suppliers within the agreed period, which cannot exceed 45 days from acceptance of goods or services. Delayed payment attracts compound interest at three times the bank rate notified by the RBI. Suppliers can file a reference with the Micro and Small Enterprises Facilitation Council through the MSME Samadhaan portal.

    The income-tax law reinforces this by allowing buyers a deduction for amounts owed to micro and small enterprises only when paid within the MSMED Act time limit. This rule, introduced as section 43B(h), has made large buyers far more careful about paying MSME suppliers on time.

    Government procurement and other concessions

    • Central ministries and public sector undertakings are required to procure a share of their purchases from micro and small enterprises.
    • Registered micro and small enterprises are generally exempt from paying earnest money deposits in government tenders.
    • Reduced official fees apply to MSMEs for trademark filings; see our trademark registration guide for how this works in practice.

    How to register on the Udyam portal

    The registration is done on the official Udyam registration portal of the Ministry of MSME. There is no fee, and no private website is needed.

    1. Keep ready the Aadhaar of the proprietor, managing partner or authorised director, the PAN of the business and, where applicable, the GSTIN.
    2. Enter the Aadhaar number and validate it through OTP.
    3. Enter the type of organisation and PAN; the portal fetches PAN details.
    4. Fill in business details: name, address, plant locations, bank details, main activity (manufacturing or services) and National Industrial Classification (NIC) codes.
    5. Provide the number of employees and investment and turnover figures. For existing businesses, these are cross-checked with income-tax and GST data.
    6. Submit with the final OTP. The Udyam Registration Number is issued, and the e-certificate can be downloaded from the portal.

    A business that has just been incorporated can register on a self-declaration basis; figures are updated once the first income-tax return is filed. Informal micro enterprises that do not have a PAN or GSTIN can obtain a certificate through the Udyam Assist Platform, which is treated as equivalent for priority sector lending.

    If you are setting up a new company, registering on Udyam soon after incorporation is a sensible step; our note on private limited company registration covers the earlier stages.

    Traders and Udyam

    Retail and wholesale traders can register on Udyam, but the registration is meant for priority sector lending purposes. Traders should check scheme-specific conditions before assuming every MSME benefit applies to them, especially the delayed payment protection, which is designed around manufacturing and service enterprises.

    Keeping your registration current

    Registration is a one-time exercise, but the details must stay accurate:

    • Update the certificate if there is a change in address, activity, ownership or bank details.
    • Watch the reclassification: category is reviewed annually using the latest ITR and GST data. Moving up from micro to small is a normal part of growth and brings its own benefits.
    • Mention the Udyam number on invoices and purchase orders so that customers recognise your status and payment timelines.
    • Customers that are companies file a half-yearly MSME return with the Registrar of Companies on dues outstanding to micro and small suppliers beyond 45 days, so accurate vendor master data helps everyone.

    Frequently asked questions

    Is Udyam registration mandatory?

    It is not mandatory for every business, but you need it to claim most MSME benefits, including delayed payment protection and scheme support.

    Is there any fee for Udyam registration?

    No. Registration on the official portal is free. Be cautious of look-alike websites that charge fees.

    Can a service business register on Udyam?

    Yes. Both manufacturing and service enterprises can register, and the same investment and turnover limits apply.

    Does Udyam registration expire?

    No. It does not need renewal, but the details should be kept updated and the classification may change each year based on filed data.

    If you would like help registering on Udyam or using your MSME status to improve collections and access to credit, we would be happy to guide you.

    This article is general information based on the law as of September 2026, and is not legal or tax advice. Please check the facts of your own case with a professional before acting.
  • LLP vs Private Limited Company: Which Structure Suits Your Business?

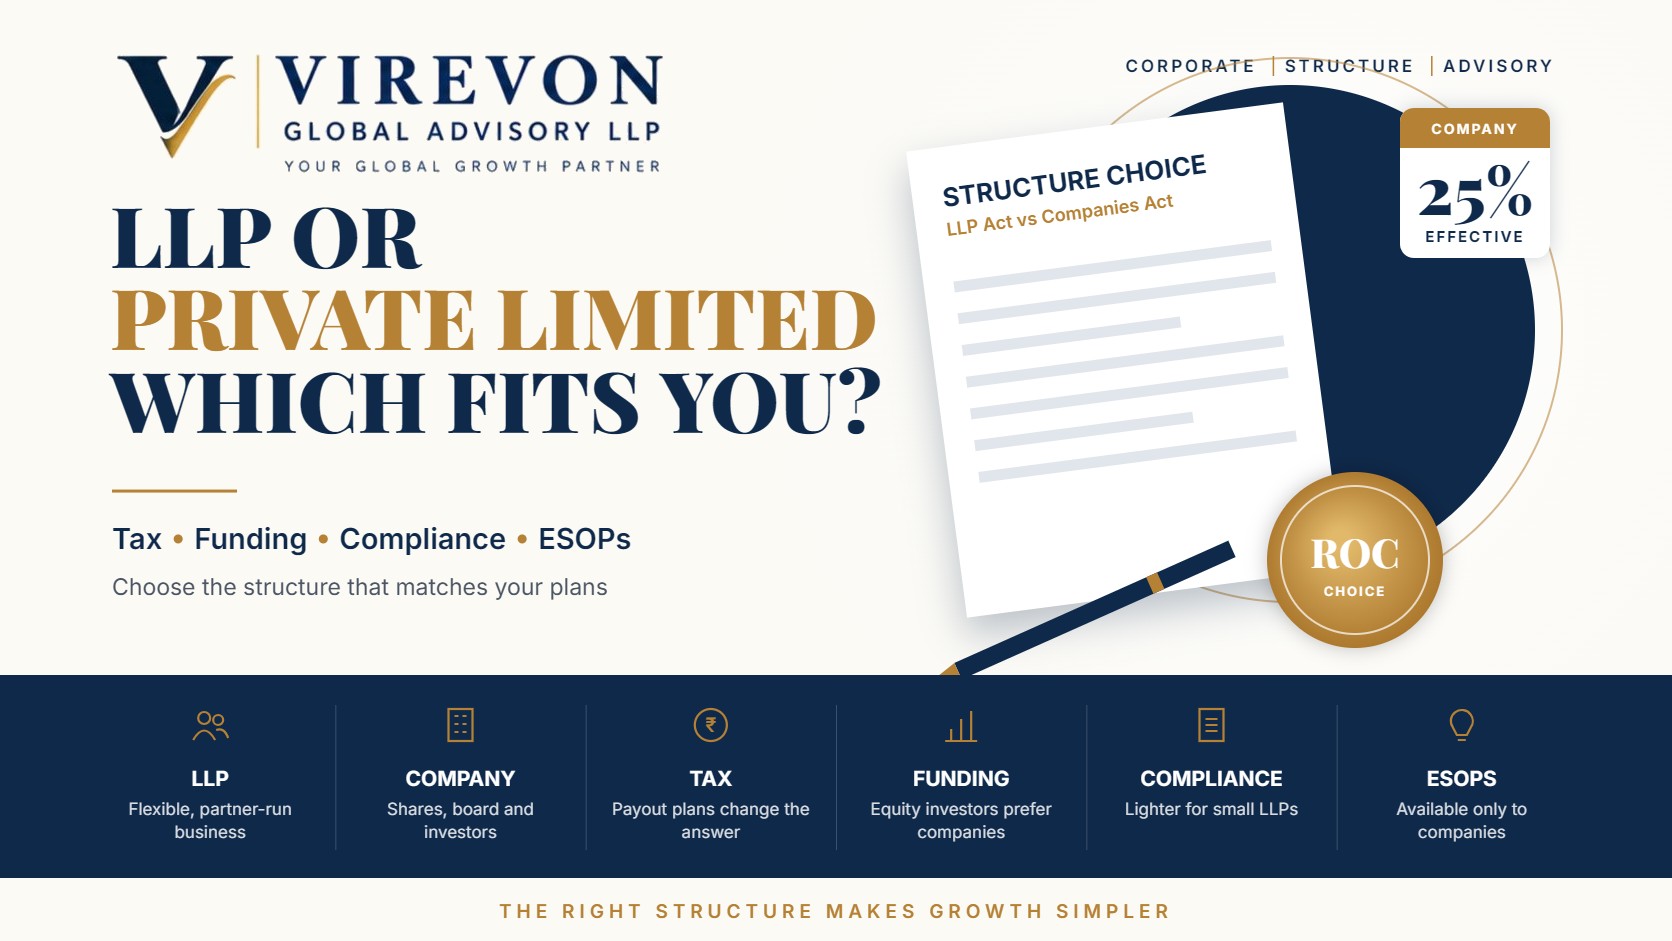
    LLP vs Private Limited Company: Which Structure Suits Your Business?

    The LLP vs private limited question comes up at the start of almost every new venture, and again when an existing business grows. Both structures give limited liability, separate legal existence and perpetual succession. The differences lie in how profits are taxed, how much compliance each demands, and how easily each can raise money or reward employees with equity.

    There is no universally better choice. A professional services firm run by three partners may be perfectly served by an LLP, while a product startup that expects to raise venture funding almost always needs a private limited company. This guide compares the two on the points that matter and works through an example.

    Key takeaways

    • An LLP suits owner-managed businesses that plan to distribute most profits and do not expect equity investors.
    • A private limited company suits businesses that plan to raise equity, issue ESOPs or retain profits for growth.
    • LLPs pay tax at 30% plus applicable surcharge and cess; profit share is not taxed again in partners’ hands.
    • Companies opting for the concessional regime pay an effective rate of about 25.17%, but dividends are taxed in shareholders’ hands.
    • A small LLP has noticeably lighter compliance than a company, which always needs an audit.

    LLP vs private limited: side-by-side comparison

    PointLLPPrivate limited company
    Governing lawLLP Act, 2008Companies Act, 2013
    Minimum ownersTwo partners, two designated partnersTwo shareholders, two directors
    OwnershipPartners’ contribution under the LLP agreementShares, easy to transfer and value
    Income tax30% plus surcharge above ₹1 crore and cessAbout 25.17% under the concessional regime
    Payout to ownersProfit share not taxed again; remuneration taxed as business income of partnersSalary taxed as salary; dividends taxed at shareholders’ slab rates
    Statutory auditOnly if turnover exceeds ₹40 lakh or contribution exceeds ₹25 lakhAlways required
    Annual ROC filingsForm 11 and Form 8AOC-4, MGT-7 or MGT-7A, plus event-based forms
    Equity fundingDifficult; most investors do not invest in LLPsStandard route for angel and venture funding
    ESOPsNot availableAvailable
    Foreign investmentAutomatic route only in sectors with 100% automatic FDI and no performance conditionsAutomatic route in most sectors

    How tax works in each structure

    LLP

    An LLP is taxed as a firm. It pays tax on its profits at 30%, with a 12% surcharge where income exceeds ₹1 crore, plus 4% cess. Partners’ share of profit is not taxed again in their hands. The LLP can pay partners remuneration and interest on capital within limits set by the income-tax law; these are deductible for the LLP and taxable for the partners.

    Private limited company

    A domestic company can opt for the concessional regime, paying 22% plus a 10% surcharge and 4% cess, an effective rate of about 25.17%, without most deductions and incentives. Directors’ salaries are deductible for the company and taxable as salary. Dividends are taxed in the shareholders’ hands at their slab rates.

    For tax year 2026-27 these rules continue under the Income-tax Act 2025, with rates set by the Finance Act. See our overview of the Income-tax Act 2025 key changes.

    A worked example

    Two founders expect a profit of ₹50 lakh before any payout to themselves. For simplicity, ignore remuneration, surcharge on individuals and other income.

    If all profit is distributed:

    • LLP: tax at 31.2% is ₹15.6 lakh. The remaining ₹34.4 lakh reaches the partners without further tax.
    • Company: tax at 25.168% is about ₹12.58 lakh. If the remaining ₹37.42 lakh is paid as dividend to shareholders in the 30% slab, their tax at 31.2% is about ₹11.67 lakh. Total tax is about ₹24.26 lakh, and ₹25.74 lakh reaches the founders.

    If most profit is retained for growth:

    • The company pays about ₹12.58 lakh and keeps ₹37.42 lakh to reinvest.
    • The LLP pays ₹15.6 lakh and keeps ₹34.4 lakh.

    The lesson: an LLP tends to be more efficient when profits are regularly distributed; a company can be more efficient when profits are reinvested, and its advantages in funding and ESOPs often outweigh the tax difference. Actual results depend on salaries, remuneration, surcharge and the founders’ other income, so model your own numbers.

    Compliance and running costs

    LLP

    • Form 11 by 30 May and Form 8 by 30 October each year. See our guide to LLP Form 8 and Form 11.
    • Audit only above the turnover or contribution thresholds.
    • Fewer mandatory meetings and registers.

    Private limited company

    • Board meetings each quarter (with relaxations for small companies), an AGM each year and statutory registers.
    • Mandatory audit, AOC-4 and MGT-7 or MGT-7A. See our guide to ROC annual filing.
    • Director KYC, auditor appointment filings and event-based forms.

    A company will usually spend more each year on professional fees and internal administration than a small LLP.

    Funding, ESOPs and exit

    • Equity funding: angel investors, venture funds and most institutional investors invest through shares. A company structure is almost essential for this.
    • ESOPs: only companies can grant stock options to employees, a key tool for startups hiring talent.
    • Debt: banks lend to both, though companies may find it easier to create charges and raise larger facilities.
    • Exit and succession: shares are easy to transfer or sell; transferring an LLP interest needs changes to the LLP agreement.
    • Conversion: an LLP can later convert into a company, but it is simpler to start with the structure you expect to need.

    A quick decision guide

    Choose an LLP if most of these apply:

    1. You are a professional or service firm run by the owners.
    2. You plan to distribute most profits each year.
    3. You do not expect to raise equity from outside investors.
    4. You want lighter compliance while the business is small.

    Choose a private limited company if most of these apply:

    1. You plan to raise angel or venture funding.
    2. You want to offer ESOPs.
    3. You plan to reinvest profits for growth.
    4. You want a structure that customers, lenders and foreign partners recognise easily.

    Ready to proceed with a company? Our guide to private limited company registration explains the SPICe+ process.

    Frequently asked questions

    Is an LLP cheaper to run than a private limited company?

    Usually yes, especially when turnover and contribution are below the audit thresholds, because a small LLP does not need a statutory audit and has fewer filings.

    Which pays less tax, an LLP or a company?

    It depends on how profits are used. An LLP often suits full distribution, while a company can be efficient when profits are retained. Model your own figures before deciding.

    Can an LLP raise venture capital?

    It is rare. Most investors require shares and a board structure, so startups planning to raise equity generally choose a private limited company.

    Can I convert my LLP into a company later?

    Yes, conversion is possible under the Companies Act, but it involves time and cost, so choose the right structure at the start where you can.

    If you are weighing an LLP against a private limited company, our team would be happy to walk through the numbers and compliance with you.

    This article is general information based on the law as of September 2026, and is not legal or tax advice. Please check the facts of your own case with a professional before acting.

  • Private Limited Company Registration in India: SPICe+ Process, Documents and Timeline

    Private Limited Company Registration in India: SPICe+ Process, Documents and Timeline

    A private limited company remains the most popular structure for start-ups and growing businesses in India. It offers limited liability, a separate legal identity and an easy route to bring in investors. The good news is that company registration in India is now almost entirely online, through a single integrated web form on the MCA portal called SPICe+.

    With complete documents, a company can often be incorporated within about a week or two, and the same process also delivers PAN, TAN and several other registrations. This guide walks through the SPICe+ process step by step, the documents you will need, the fees involved and a realistic timeline.

    Key takeaways

    • SPICe+ is a single web form with Part A for name reservation and Part B for incorporation, filed on the MCA V3 portal.
    • A private limited company needs at least two directors and two shareholders, with at least one director resident in India.
    • The government incorporation fee is nil for companies with authorised capital up to ₹15 lakh, but state stamp duty is payable.
    • Linked forms include the e-MOA, e-AOA and AGILE-PRO-S, which covers GST, EPFO, ESIC, profession tax and a bank account where applicable.
    • After incorporation, the declaration of commencement of business in INC-20A should be filed within 180 days.

    Before you start: basic requirements

    • Directors: minimum two, maximum fifteen (more with a special resolution). At least one director must have stayed in India for at least 182 days in the financial year.
    • Shareholders: minimum two, maximum two hundred. Directors can also be shareholders.
    • Registered office: an address in India where the company can receive communications. It can be rented, owned or even a residential address, with the owner’s consent.
    • Digital signatures (DSC): every director and subscriber signing the forms needs a valid Class 3 DSC.
    • Capital: there is no minimum paid-up capital requirement, but choose authorised capital with future funding in mind.

    Company registration in India through SPICe+: step by step

    Step 1: Choose and reserve a name (SPICe+ Part A)

    Propose up to two names that reflect the business and are not identical or too similar to existing companies, LLPs or registered trademarks. Check the MCA name search and the trademark registry before filing. Once approved, the name is reserved for 20 days, within which Part B must be filed. You can also file Part A and Part B together.

    Choosing a distinctive name early also helps with branding; our guide to trademark registration in India explains how to protect it.

    Step 2: Fill in SPICe+ Part B

    Part B collects the core incorporation details:

    • Registered office address and proof
    • Authorised and subscribed share capital
    • Details of directors and subscribers, including DIN allotment for up to three new directors
    • PAN and TAN applications, which are processed automatically

    Step 3: Prepare the linked forms

    1. e-MOA (INC-33): the Memorandum of Association, including the company’s main objects.
    2. e-AOA (INC-34): the Articles of Association, the internal rules of the company.
    3. AGILE-PRO-S: for GSTIN (if opted), EPFO and ESIC registration, profession tax in applicable states, and opening a bank account.
    4. INC-9: the declaration by subscribers and directors, generated by the system.

    Step 4: Sign, pay and submit

    Affix DSCs on all forms, upload them and pay the fees and stamp duty online. The Central Registration Centre processes the application.

    Step 5: Certificate of incorporation

    Once approved, you receive the Certificate of Incorporation with the Corporate Identity Number (CIN), along with PAN and TAN. EPFO and ESIC registration numbers are also allotted, and GST registration follows where it was applied for.

    Documents checklist

    For each director and subscriberFor the registered office
    PAN cardUtility bill (electricity, gas, water or telephone), not older than two months
    Aadhaar or other identity proofRent agreement or ownership proof
    Address proof such as bank statement or utility bill, recentNo-objection letter from the owner
    Passport-size photographPhotographs of the premises, if asked
    Email ID and mobile number
    DSC

    Foreign nationals and NRIs need a passport and, typically, notarised or apostilled documents, depending on the country.

    Fees and timeline

    Government fees: for authorised capital up to ₹15 lakh, the incorporation fee is nil. Name reservation and higher capital attract fees on the MCA fee scale.

    Stamp duty: payable on the MOA, AOA and share capital, at rates that vary by state. The portal calculates it automatically.

    Timeline: a common range is about 7 to 15 working days from the start, depending on:

    • How quickly DSCs are issued
    • Whether the name is approved at the first attempt
    • Completeness of documents, since resubmission requests add days

    After incorporation: the first 180 days

    Registration is only the beginning. Early compliance keeps the company in good standing:

    1. Open the bank account and deposit subscription money from shareholders.
    2. File INC-20A, the declaration of commencement of business, within 180 days of incorporation, with proof of subscription money received.
    3. Appoint the first auditor within 30 days of incorporation.
    4. Hold the first board meeting within 30 days, and at least four board meetings each year thereafter, subject to relaxations for certain companies.
    5. Issue share certificates to subscribers within the prescribed time.
    6. Plan annual filings such as AOC-4 and MGT-7; see our guide to ROC annual filing.

    If you are still deciding on the structure, our comparison of LLP vs private limited company may help.

    Frequently asked questions

    How long does company registration in India take?

    With complete documents and valid DSCs, a private limited company can often be incorporated in about 7 to 15 working days. Name objections or resubmissions can extend this.

    Is there a minimum capital for a private limited company?

    No. There is no minimum paid-up capital requirement. Choose authorised capital based on your funding plans, as stamp duty and fees depend on it.

    Can a foreign national be a director?

    Yes. A foreign national can be a director and shareholder, but at least one director must be resident in India. Foreign investment must also follow FEMA rules.

    Do I need GST registration at the time of incorporation?

    Not necessarily. GST registration is required when you cross the threshold or fall into a compulsory category. It can be applied for through AGILE-PRO-S or later.

    If you would like help registering your private limited company and setting up the first-year compliance, our team would be happy to assist.

    This article is general information based on the law as of September 2026, and is not legal or tax advice. Please check the facts of your own case with a professional before acting.