Tag: Late fee

  • Belated and Revised Income Tax Returns: Deadlines, Fees and Practical Tips

    Belated and Revised Income Tax Returns: Deadlines, Fees and Practical Tips

    Missed the ITR due date for FY 2025-26, or spotted a mistake after filing? The Income-tax law gives you two remedies — the belated return and the revised return. Understanding the belated return revised return rules helps you act in time, keep costs low and avoid losing valuable benefits.

    Returns for FY 2025-26 (assessment year 2026-27) are still governed by the Income-tax Act, 1961, even though the Income-tax Act, 2025 came into force on 1 April 2026. This guide covers the key dates, fees, the benefits you may lose by filing late, and practical tips for both situations.

    Key takeaways

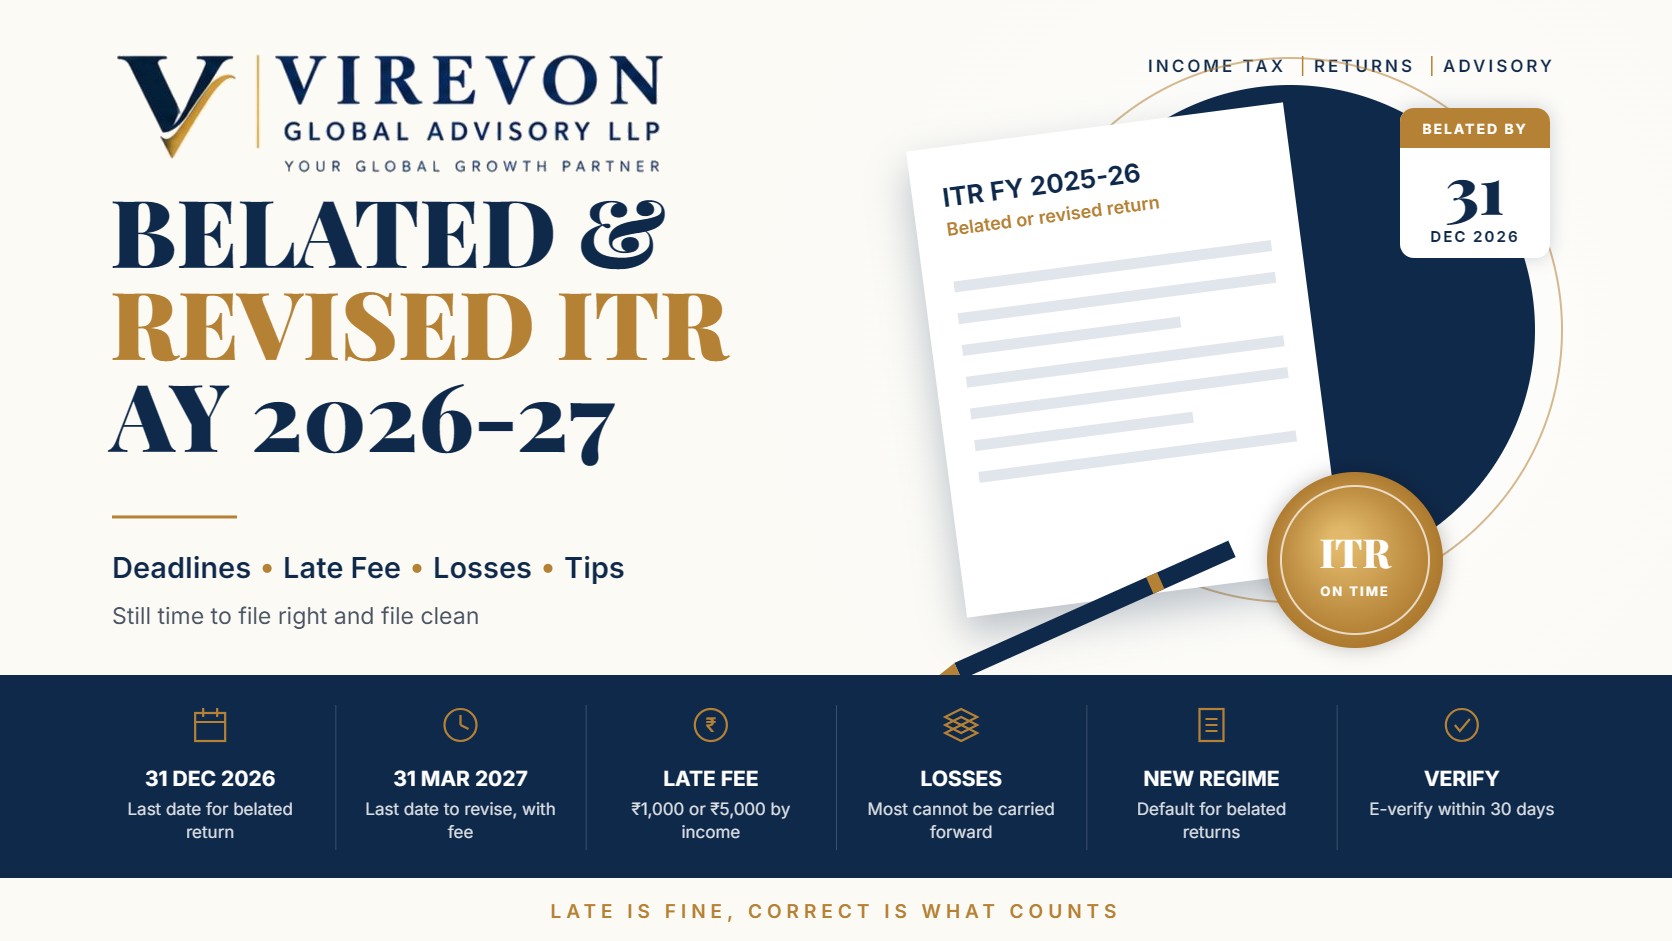
    • A belated return for FY 2025-26 can be filed up to 31 December 2026, or before assessment is completed, whichever is earlier.
    • A revised return can be filed up to 31 March 2027, or before assessment is completed, whichever is earlier.
    • A late fee of up to ₹5,000 applies to belated returns (₹1,000 where total income does not exceed ₹5 lakh), along with interest on unpaid tax.
    • From 2026, a revised return filed after 31 December attracts a separate fee of ₹1,000 or ₹5,000.
    • Business and capital losses cannot be carried forward in a belated return, and the old tax regime is generally not available.

    Belated return vs revised return at a glance

    PointBelated return (s. 139(4))Revised return (s. 139(5))
    PurposeFiling after the original due dateCorrecting a return already filed
    Last date for FY 2025-2631 December 202631 March 2027
    FeeUp to ₹5,000 under section 234FNil up to 31 Dec 2026; ₹1,000 or ₹5,000 after that under section 234I
    InterestSection 234A on unpaid taxAs applicable to the corrected tax
    Can it be revised?Yes, within the revised return time limitYes, more than once, within the time limit
    LossesMost losses cannot be carried forwardSame as the original return

    Original due dates for FY 2025-26

    For context, the original due dates for AY 2026-27 were:

    • 31 July 2026 — individuals and HUFs filing ITR-1 or ITR-2 without a tax audit.
    • 31 August 2026 — ITR-3 and ITR-4 cases not requiring a tax audit.
    • 31 October 2026 — taxpayers requiring a tax audit, and partners of such firms.
    • 30 November 2026 — cases requiring a transfer pricing report.

    If you missed your due date, the belated return is your next step. Our tax audit checklist for FY 2025-26 covers the audit-linked timelines.

    What you lose by filing a belated return

    Filing late is always better than not filing, but a few benefits are lost:

    1. Carry forward of losses: business losses, speculation losses and capital losses of the year cannot be carried forward. Unabsorbed depreciation and house property loss remain available.
    2. Choice of tax regime: the new tax regime is the default. Individuals without business income can choose the old regime only in a return filed by the due date, and those with business income must have filed the option form by the due date. A belated return therefore generally follows the new regime.
    3. Certain deductions: some profit-linked deductions require the return to be filed by the due date.
    4. Interest on tax: interest under section 234A runs at 1% per month or part of a month on the unpaid tax from the due date.

    When and how to revise a return

    A revised return is the right tool when you discover an omission or a wrong statement in a return already filed — for example, a missed deduction, a wrong bank account, an unreported interest credit or an incorrect TDS claim.

    Useful points:

    • You can revise an original or belated return.
    • You can revise more than once; the latest valid revised return replaces the earlier ones.
    • The revised return must be complete in itself, not just the change.
    • Select “revised” in the filing section and quote the acknowledgement number and date of the original return.
    • E-verify within 30 days, or the return may be treated as not filed.

    If the revision window has passed and you need to report more income, the updated return (ITR-U) may help, at the cost of additional tax.

    Late fee and fee on revised return

    Section 234F (belated returns):

    • ₹5,000 where total income exceeds ₹5 lakh.
    • ₹1,000 where total income does not exceed ₹5 lakh.

    Section 234I (revised returns, inserted in 2026): a revised return filed after 31 December 2026 but by 31 March 2027 attracts a fee of ₹1,000 (income up to ₹5 lakh) or ₹5,000 (other cases). The practical message is to revise before the calendar year ends where you can.

    Any tax due must be paid with interest before filing; the return will not be complete otherwise.

    Practical tips for a smooth filing

    • Reconcile AIS, TIS and Form 26AS before filing so the return matches the department’s data.
    • Pay self-assessment tax first and enter the challan details carefully.
    • Double-check bank details and pre-validate the refund account.
    • Keep working papers for deductions and exemptions claimed.
    • Respond promptly to intimations — see our guide on section 143(1) intimations if you receive one.
    • Do not wait for the last week of December or March; portal traffic is heavy and small errors become hard to fix.

    Frequently asked questions

    Can I file a belated return after 31 December 2026?

    No. After that date, the only route to file for FY 2025-26 is an updated return (ITR-U), which carries additional tax and cannot be used to claim a refund.

    Can I claim a refund in a belated return?

    Yes. A refund can be claimed in a belated return, and interest on the refund is generally computed from the date of filing rather than from 1 April.

    Can I change from the new regime to the old regime in a revised return?

    Only if the original return was filed by the due date with the old regime available to you. A belated return generally cannot opt for the old regime, and revising it does not change that.

    Will a revised return trigger scrutiny?

    Revising a return is a normal, legitimate correction. Scrutiny depends on risk parameters, not on the fact of revision alone. Keeping clear records supports your position either way.

    If you need help filing a belated or revised return for FY 2025-26, our team is happy to guide you through it quickly and carefully.

    This article is general information based on the law as of September 2026, and is not legal or tax advice. Please check the facts of your own case with a professional before acting.
  • GST Interest and Late Fees: Section 50 and Section 47 Explained with Examples

    GST Interest and Late Fees: Section 50 and Section 47 Explained with Examples

    Paying GST a few days late is common, especially when customer receipts arrive after the due date. The cost of that delay comes in two parts: GST interest under section 50 of the CGST Act, which applies to tax paid late, and a late fee under section 47, which applies to returns filed late. The two work quite differently, and knowing how each is calculated makes it much easier to plan cash flow and keep these costs small.

    This guide explains both provisions in plain language, with worked examples, the current late fee caps for the main returns and a short checklist for finance teams.

    Key takeaways

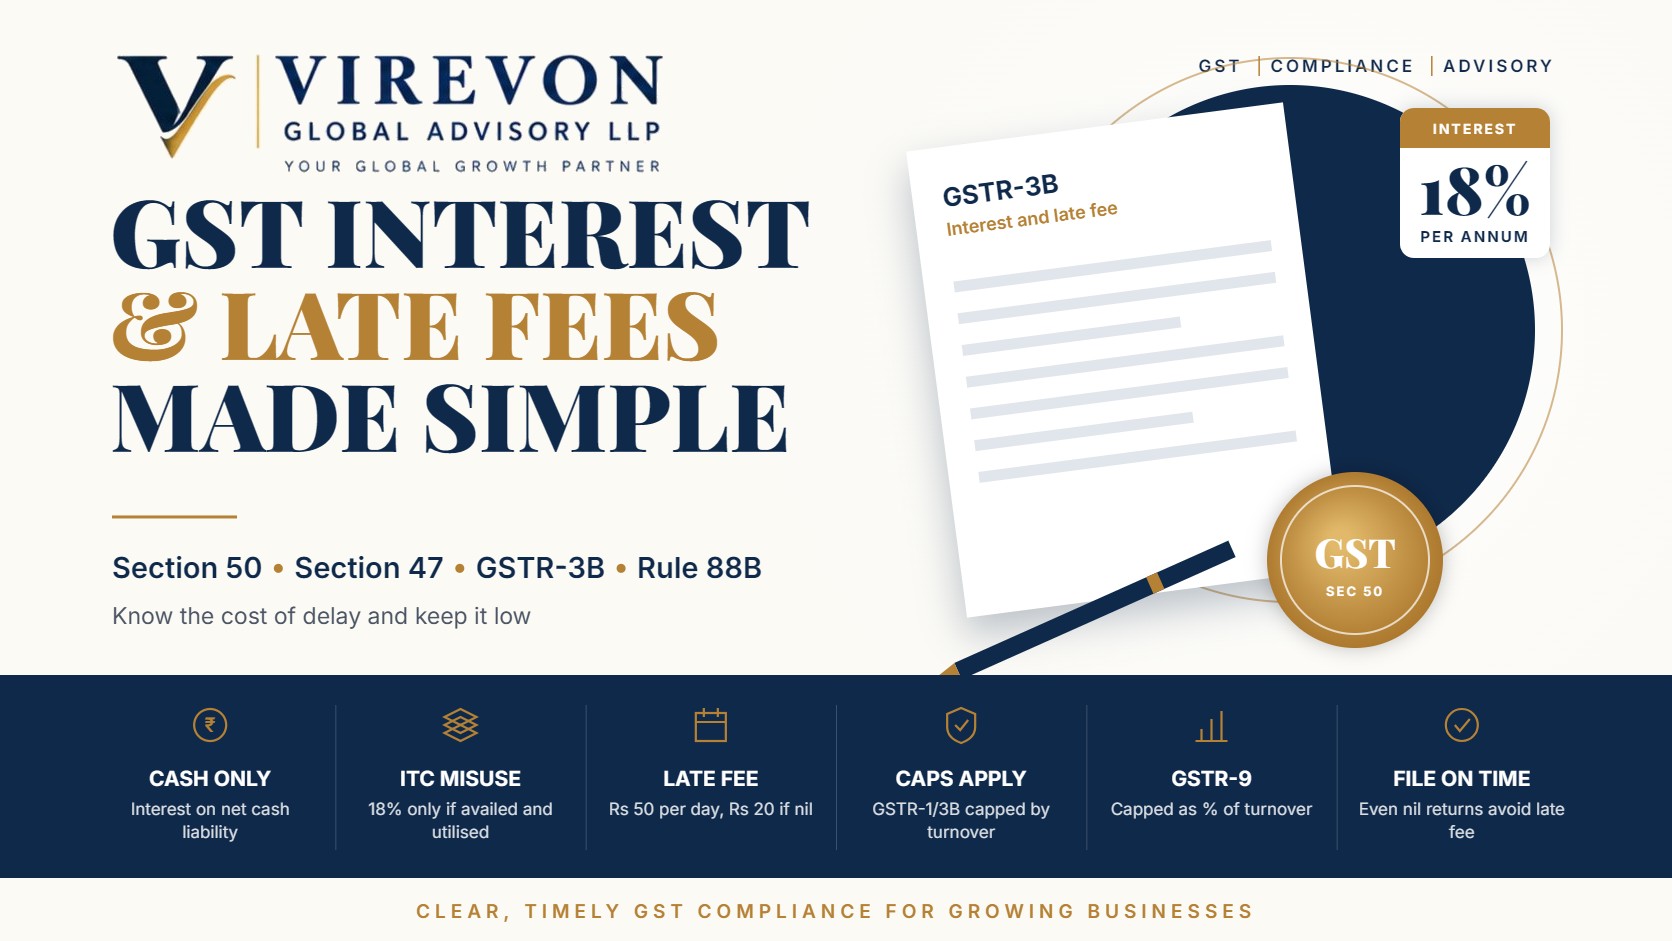
    • Interest under section 50(1) is 18% per annum, calculated on the tax paid in cash for the period of delay, not on the gross liability.
    • Interest on input tax credit (ITC) wrongly availed applies only when that credit is also utilised, and is charged at 18% per annum under the notified rate.
    • The late fee under section 47 is a fixed daily amount (currently ₹50 per day, or ₹20 for nil returns, for GSTR-1 and GSTR-3B), with turnover-based caps.
    • GSTR-9 has its own late fee slabs, capped as a percentage of turnover in the State or Union territory.
    • Interest and late fee are both payable in cash; they cannot be set off against ITC.

    How GST interest under section 50 works

    Section 50 has two main limbs.

    Section 50(1) — delayed payment of tax. When tax is paid after the due date, interest is payable at the notified rate of 18% per annum from the day after the due date until the day of payment. A proviso, inserted with effect from 1 July 2017, limits this interest to the portion of tax paid through the electronic cash ledger when the return for that period is filed late. The exception is where the return is filed only after proceedings under section 73 or 74 have started; in that case interest can be computed on the full amount.

    In practice, if your GSTR-3B liability is largely covered by ITC, the interest cost of a short delay is modest because only the cash portion attracts it.

    Section 50(3) — ITC wrongly availed and utilised. The Act allows a rate of up to 24%, but the notified rate is 18% per annum. Following the amendment made effective from 1 July 2017, interest applies only where the ineligible credit has been both availed and utilised. Rule 88B of the CGST Rules explains when credit is treated as utilised: broadly, when the balance in the electronic credit ledger falls below the amount of wrongly availed ITC, to the extent of that shortfall. So credit that simply sat in the ledger unused and was later reversed usually does not attract interest.

    Worked example: GST interest on delayed GSTR-3B

    Assume a monthly filer has the following for August 2026 (GSTR-3B due 20 September 2026):

    ItemAmount
    Output tax liability₹2,00,000
    ITC available and used₹1,40,000
    Net tax paid in cash₹60,000
    Actual filing and payment date10 October 2026
    Days of delay20

    Interest under section 50(1) = ₹60,000 × 18% × 20 / 365 = about ₹592.

    If interest had wrongly been computed on the gross ₹2,00,000, it would come to roughly ₹1,973. This is why checking the cash-ledger basis is worthwhile before paying any interest demand.

    Example: wrongly availed ITC

    Suppose ₹50,000 of ineligible ITC was claimed in June. The credit ledger balance stayed above ₹50,000 until 15 August, when it fell to ₹20,000. Under Rule 88B, ₹30,000 is treated as utilised from that date. If the credit is reversed on 14 September, interest runs on ₹30,000 for 30 days: ₹30,000 × 18% × 30 / 365 = about ₹444. The ₹20,000 that stayed in the ledger does not attract interest.

    Late fee under section 47

    Section 47 prescribes a late fee for returns filed after the due date. The Act sets ₹100 per day under CGST (and a matching amount under the State Act), but the Government has notified reduced amounts and maximum caps. For GSTR-1 and GSTR-3B, the current position for tax periods from June 2021 onwards is:

    CategoryLate fee per day (CGST + SGST)Maximum per return
    Nil return₹20₹500
    Turnover up to ₹1.5 crore₹50₹2,000
    Turnover ₹1.5 crore to ₹5 crore₹50₹5,000
    Turnover above ₹5 crore₹50₹10,000

    Turnover here refers to aggregate turnover in the preceding financial year. For the example above, a 20-day delay would attract a late fee of 20 × ₹50 = ₹1,000, well within the cap.

    Late fee for GSTR-9

    For the annual return, the notified daily late fee is ₹50 for turnover up to ₹5 crore, ₹100 for turnover between ₹5 crore and ₹20 crore, and ₹200 above ₹20 crore (CGST and SGST combined). The maximum is 0.04% of turnover in the State or Union territory for the first two slabs and 0.5% for the highest slab. Since the annual return is due by 31 December, it helps to start the reconciliation early; our GSTR-9 and GSTR-9C checklist covers the preparation steps.

    How interest and late fee are paid

    • The GST portal computes the late fee automatically when a return is filed after its due date, and it must be paid before the return can be filed.
    • For GSTR-3B, the portal shows system-computed interest for the previous period in the next return. You can accept it or revise it with reasons, but the figure should be accurate and supportable.
    • Both amounts are payable only through the electronic cash ledger.
    • Interest or tax found short later can be paid voluntarily through Form DRC-03, which often avoids a notice. Our guide on DRC-03 voluntary payment explains the process.

    Practical checklist to keep costs low

    1. File even when you cannot pay in full. Under GST, a return generally cannot be filed without paying the tax shown, so plan cash for the 20th of each month (or the relevant QRMP date).
    2. File nil returns on time. Nil returns carry a small fee, but it adds up across months and GSTINs.
    3. Keep ITC eligibility checks monthly. Reversing an ineligible credit before it is utilised avoids section 50(3) interest altogether.
    4. Track the credit ledger balance when you discover an ineligible claim; the Rule 88B computation depends on the lowest balance after the wrong claim.
    5. Verify notice computations. Check the rate, the base (cash versus gross) and the number of days before paying.
    6. Maintain a compliance calendar covering GSTR-1, GSTR-3B, IMS actions and annual returns for every registration.

    Frequently asked questions

    Is GST interest under section 50 calculated on gross or net tax?

    For a return filed late, interest is calculated on the tax paid through the electronic cash ledger. The exception is where the return is filed only after proceedings under section 73 or 74 have begun.

    What is the current late fee for a nil GSTR-3B?

    ₹20 per day (₹10 CGST and ₹10 SGST), capped at ₹500 per return.

    Can interest or late fee be paid using ITC?

    No. Both must be paid in cash through the electronic cash ledger.

    Is interest payable if wrong ITC was never used?

    Generally no. Section 50(3) applies only when ineligible ITC is availed and utilised, and Rule 88B explains how utilisation is measured using the credit ledger balance.

    If you would like help checking an interest demand, planning GST payments or setting up a reliable filing calendar, our team is happy to assist.

    This article is general information based on the law as of September 2026, and is not legal or tax advice. Please check the facts of your own case with a professional before acting.