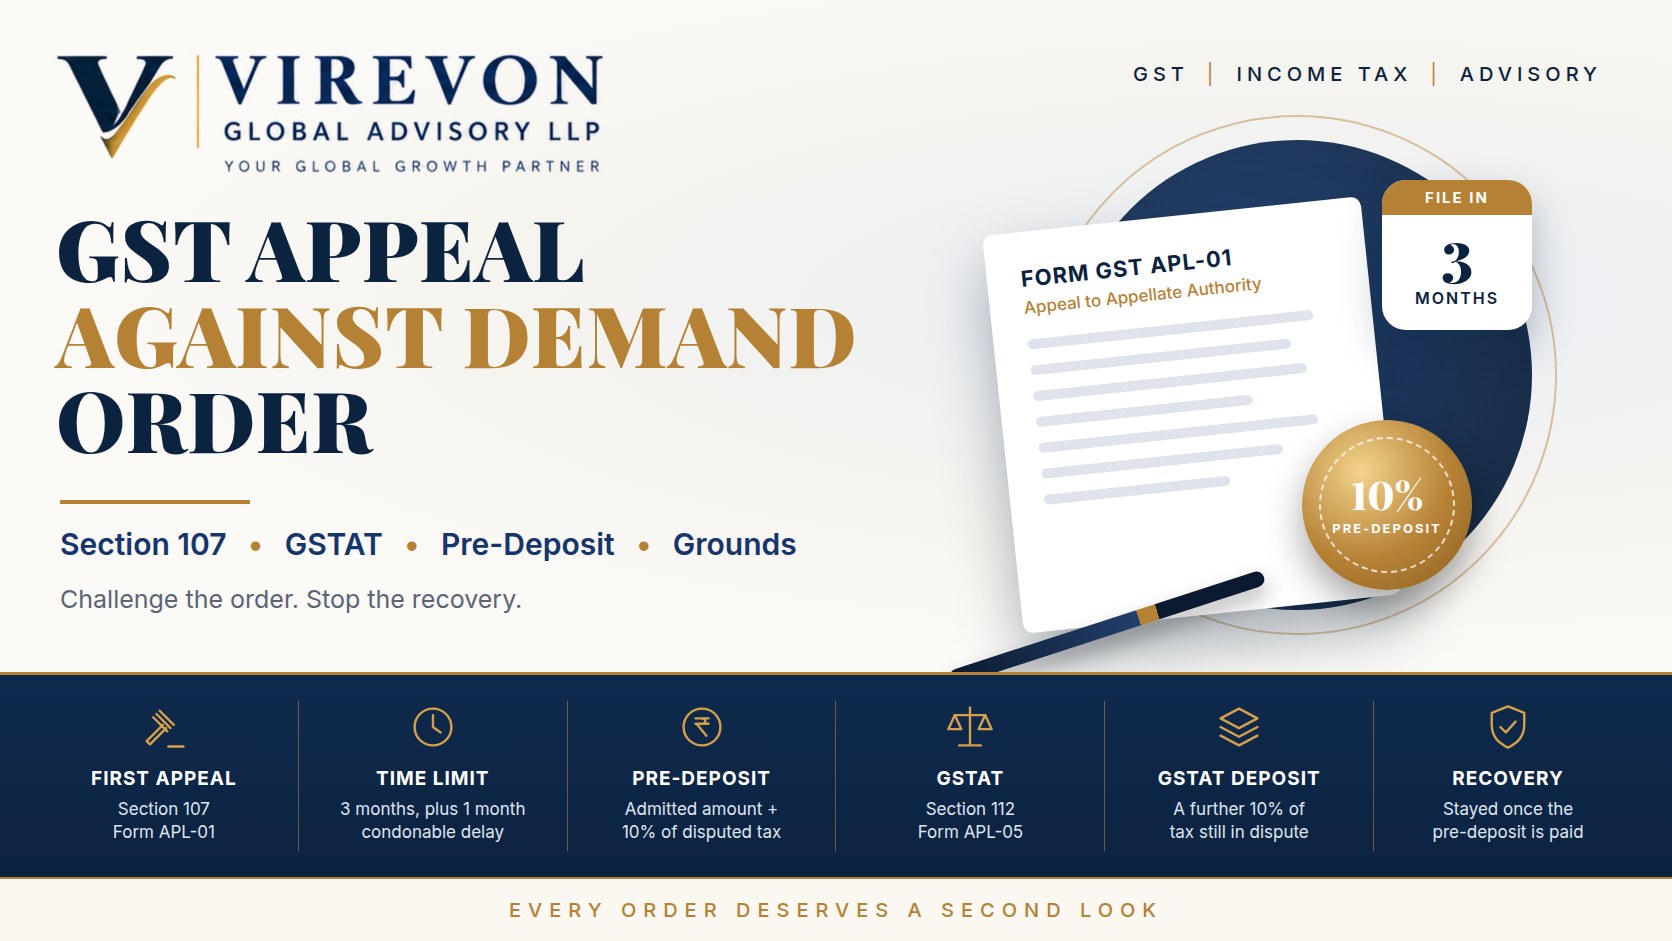
When a GST officer passes a demand order (summary in Form DRC-07), recovery can start soon afterwards, including attachment of bank accounts. An appeal filed on time with the required pre-deposit stops recovery of the balance and gives you a fresh hearing on the merits. This guide covers both stages: the first appeal and the GST Appellate Tribunal (GSTAT).
Stage 1: Appeal to the Appellate Authority (Section 107)
- Form: APL-01, filed online on the GST portal
- Time limit: 3 months from the date the order is communicated. The Appellate Authority can condone a further 1 month of delay for sufficient cause, but no more.
- Pre-deposit: the full amount of tax, interest, fine, fee and penalty that you admit, plus 10% of the disputed tax (subject to the statutory cap)
- Effect: once the pre-deposit is paid, recovery of the balance is deemed stayed
Stage 2: Appeal to the GST Appellate Tribunal (Section 112)
GSTAT has now started functioning and accepting appeals, which gives taxpayers a real second forum after years of waiting.
- Form: APL-05
- Time limit: 3 months from communication of the first appellate order
- Pre-deposit: a further 10% of the tax that remains in dispute, over and above the first-stage pre-deposit
- Backlog appeals: special cut-off dates were notified for orders passed before GSTAT became operational. If you have an older appellate order that was never taken further, check at once whether a window is still open.
Grounds that carry weight in GST appeals
- Limitation: SCN or order issued after the time limit in Section 73, 74 or 74A
- Wrong section: for example, Section 73 or 74 invoked for FY 2024-25, where Section 74A applies
- Natural justice: no personal hearing, or the reply not considered
- Order beyond the SCN: the demand exceeds or differs from what was proposed
- Merits: genuine ITC denied only for a 2A/2B mismatch, classification or valuation errors, or duplicate demands
Practical checklist before filing
- Get the certified order, the SCN and your reply together in one file.
- Calculate the pre-deposit exactly and pay it through the electronic cash or credit ledger, as permitted.
- Draft the statement of facts and the grounds of appeal. Weak grounds cannot easily be added later.
- Keep proof of filing and payment, and write to the proper officer asking that recovery be stayed.
Watch the calendar
For FY 2022-23, orders under Section 73 must be passed by 31 December 2026. A large number of orders can be expected in the last quarter of 2026, which puts their 3-month appeal windows in early 2027. If you have a pending SCN for that year, prepare your appeal file now.
Received a GST demand order? Send it on WhatsApp. We will check the time limit, the pre-deposit and the grounds.
Read more: GST appeal services · Show cause notices under Section 73, 74 and 74A
This article is general information and is not legal advice. Pre-deposit percentages and caps are as per the CGST Act as amended; confirm the current position for your case.
Leave a Reply