Tag: ROC Filing

  • LLP Annual Compliance: Form 8 and Form 11 Due Dates and Late Fees

    LLP Annual Compliance: Form 8 and Form 11 Due Dates and Late Fees

    Every Limited Liability Partnership registered in India has two annual filings with the Registrar, whether or not it did any business during the year: the annual return and the statement of accounts and solvency. Together, LLP Form 8 Form 11 make up the core of LLP annual compliance, and missing either one leads to additional fees that grow with every day of delay.

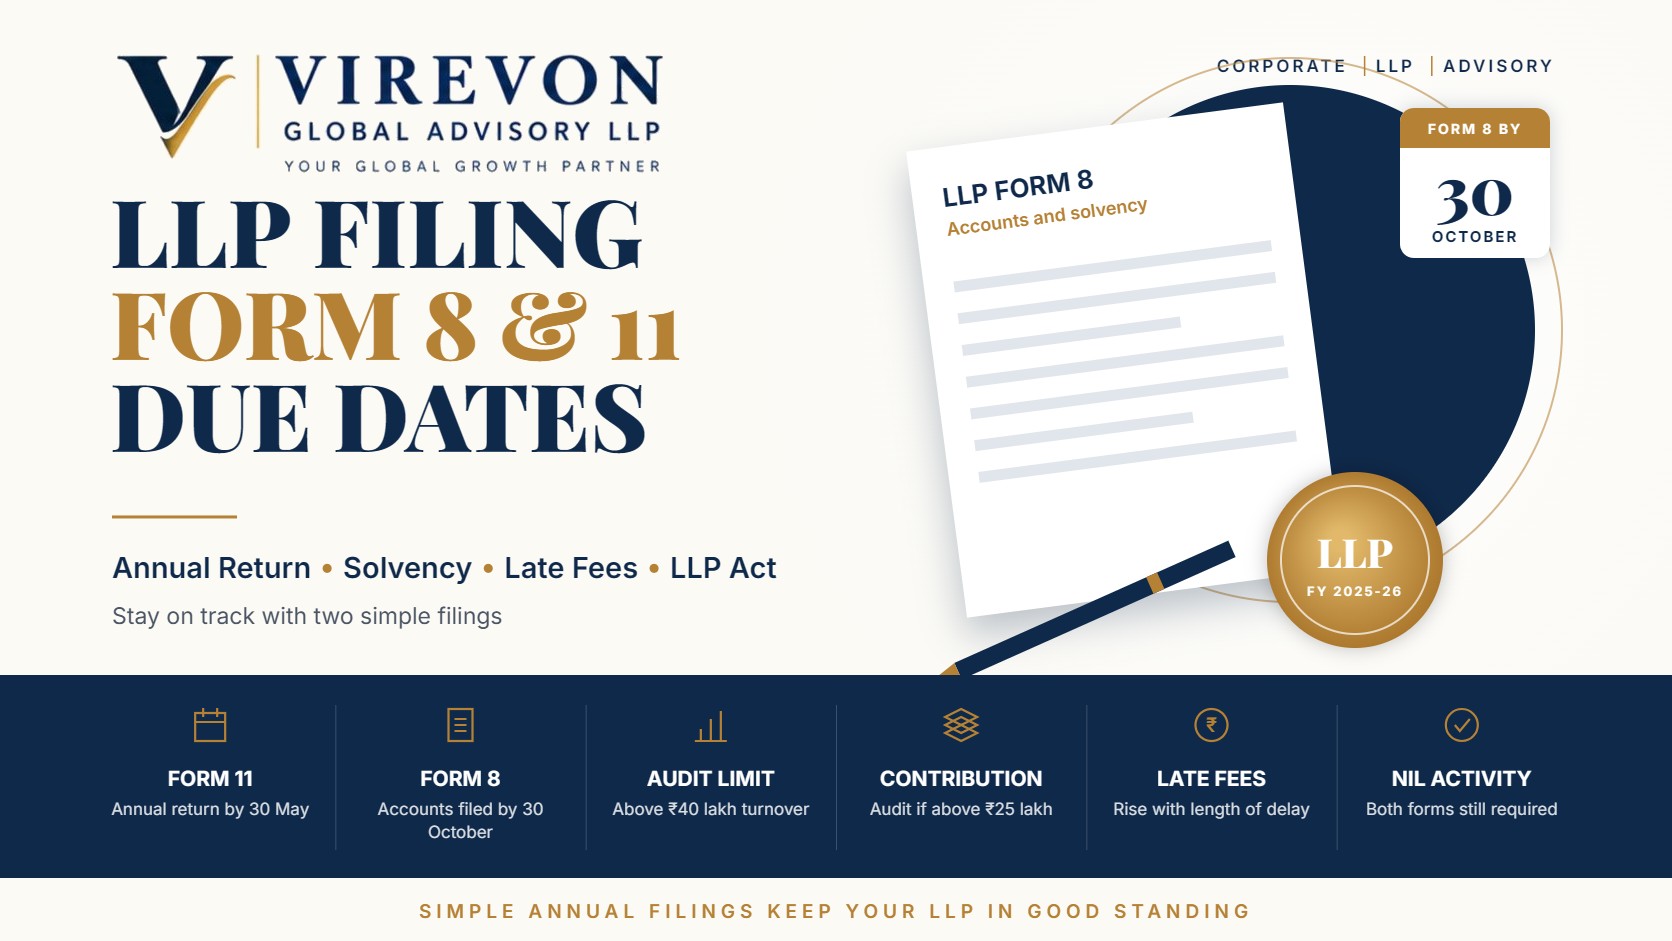
    For FY 2025-26, Form 11 was due on 30 May 2026, and Form 8 is due on 30 October 2026. If your LLP has filed Form 11 but not yet Form 8, now is a good time to finalise the accounts. This guide explains what each form contains, the due dates, the additional fees and penalties, and the practical steps to file without stress.

    Key takeaways

    • Form 11 (annual return) is due within 60 days of the year end, that is by 30 May; Form 8 (statement of account and solvency) is due within 30 days of the end of six months from the year end, that is by 30 October.
    • Both forms must be filed even if the LLP had no business or turnover during the year.
    • Late filing attracts an additional fee calculated as multiples of the normal fee, rising with the length of delay, with per-day amounts after one year.
    • Separate penalties may apply to the LLP and its designated partners under sections 34 and 35 of the LLP Act, 2008.
    • LLPs with turnover above ₹40 lakh or contribution above ₹25 lakh must have their accounts audited before filing Form 8.

    LLP Form 8 and Form 11 at a glance

    ParticularsForm 11Form 8
    PurposeAnnual return: partners, contribution and changesStatement of account and solvency
    Legal basisSection 35 of the LLP ActSection 34 of the LLP Act
    Due date for FY 2025-2630 May 202630 October 2026
    Signed byDesignated partner, with professional certification in larger LLPsDesignated partners, certified by a practising professional
    Required with nil activityYesYes

    Form 11: the annual return

    Form 11 captures the LLP’s structure for the year: details of designated partners and partners, their contributions, changes during the year, and summary information such as total contribution and whether the LLP has any penalties or compounding. Larger LLPs, broadly those with turnover above ₹5 crore or contribution above ₹50 lakh, need the form certified by a practising company secretary. For others, the designated partner’s certification is sufficient.

    Because it is based on the partner register rather than the accounts, Form 11 is quick to prepare. The most common issues are mismatches between contribution shown in Form 11 and in the LLP agreement or Form 8, and unreported changes in partners, which should have been filed separately through Form 4.

    Form 8: statement of account and solvency

    Form 8 has two parts.

    • Part A, statement of solvency: a declaration by the designated partners on whether the LLP can pay its debts in the normal course of business.
    • Part B, statement of accounts: the statement of assets and liabilities and the statement of income and expenditure for the year, with key figures such as contribution, secured and unsecured loans, turnover and profit.

    The form is signed by two designated partners and certified by a practising professional. If the LLP’s accounts are required to be audited, the audited figures are used.

    When is an audit required?

    Under the LLP rules, the accounts must be audited if the LLP’s turnover exceeds ₹40 lakh or its contribution exceeds ₹25 lakh in a financial year. Where neither limit is crossed, audit is optional unless the LLP agreement requires it. Remember that a tax audit under the Income-tax Act is a separate requirement with its own thresholds; our guide on the tax audit for FY 2025-26 covers it.

    Additional fees for late filing

    The LLP rules replaced the old flat per-day additional fee with a slab system. If Form 8 or Form 11 is filed late, the additional fee is a multiple of the normal filing fee, and the multiple increases with the length of the delay. The multiples are lower for small LLPs and higher for other LLPs. Once the delay exceeds 360 days, a per-day amount is added on top, currently ₹10 per day for a small LLP and ₹20 per day for other LLPs.

    The normal filing fee itself depends on the LLP’s contribution, ranging from ₹50 for contribution up to ₹1 lakh to ₹600 for contribution above ₹1 crore. The fee is calculated automatically on the MCA portal, so the practical point is simple: the longer the delay, the higher the cost.

    What counts as a small LLP?

    The LLP Act defines a small LLP by reference to contribution and turnover. The default limits in the Act are contribution up to ₹25 lakh and turnover up to ₹40 lakh, and the rules can prescribe higher limits. Check the current prescribed limits before relying on small LLP treatment, as it affects both fees and penalties.

    Penalties under the LLP Act

    Apart from the additional fee, the Registrar can levy penalties:

    • Section 34 (accounts and solvency): the LLP and each designated partner may face a penalty of ₹100 per day of default, subject to a maximum of ₹1 lakh for the LLP and ₹50,000 for each designated partner.
    • Section 35 (annual return): similar per-day penalties with similar maximums.

    Small LLPs benefit from lower penalties under the Act. Prolonged non-filing can also result in the Registrar treating the LLP as defunct and initiating strike-off, and designated partners may face difficulty in future appointments.

    A simple annual compliance calendar

    1. By 30 May: file Form 11 for the previous year.
    2. By 31 July: file the income tax return in ITR-5 if no audit is needed. For FY 2025-26, audited cases now have until 21 November 2026 under the extension announced by the CBDT.
    3. By 30 October: file Form 8 with the approved (and, where required, audited) accounts.
    4. Throughout the year: file event-based forms such as Form 3 for changes in the LLP agreement and Form 4 for partner changes within 30 days of the change.
    5. Every year: complete DIR-3 KYC for designated partners who hold a DIN.

    If your business operates as a company rather than an LLP, see our guide to AOC-4 and MGT-7 due dates. Filing status can be checked on the MCA portal.

    Frequently asked questions

    What is the due date for LLP Form 8 for FY 2025-26?

    Form 8 is due on 30 October 2026, within 30 days from the end of six months after the financial year closes.

    What is the due date for LLP Form 11?

    Form 11 is due within 60 days of the end of the financial year, that is, by 30 May each year. For FY 2025-26, it was due on 30 May 2026.

    Does a dormant LLP need to file Form 8 and Form 11?

    Yes. Both forms are mandatory for every registered LLP, even if it had no transactions during the year.

    Is there a late fee cap for LLP forms?

    No. The additional fee increases in slabs as the delay grows and continues on a per-day basis after 360 days, so early filing is the most economical option.

    If you would like support preparing and filing your LLP Form 8 and Form 11, our team would be happy to help.

    This article is general information based on the law as of September 2026, and is not legal or tax advice. Please check the facts of your own case with a professional before acting.

  • ROC Annual Filing for FY 2025-26: AOC-4 and MGT-7 Due Dates and Penalties

    ROC Annual Filing for FY 2025-26: AOC-4 and MGT-7 Due Dates and Penalties

    For most private companies, the annual general meeting (AGM) for FY 2025-26 had to be held by 30 September 2026. That date sets the clock for the two main ROC filings of the year, and the AOC-4 MGT-7 due date follows directly from it: financial statements within 30 days of the AGM and the annual return within 60 days.

    The good news is that both forms are routine once the audited accounts and board records are in place. This guide sets out the dates for FY 2025-26, the forms that apply to different types of companies, the additional fees and penalties for delay, and a simple checklist to help your filings go through the MCA V3 portal without resubmissions.

    Key takeaways

    • With an AGM on 30 September 2026, AOC-4 is due by 30 October 2026 and MGT-7 or MGT-7A by 29 November 2026.
    • One Person Companies file AOC-4 within 180 days of the financial year end, which for FY 2025-26 was 27 September 2026.
    • Small companies now include those with paid-up capital up to ₹10 crore and turnover up to ₹100 crore, following the revised definition effective 1 December 2025.
    • Late filing attracts an additional fee of ₹100 per day per form, with no upper limit, plus possible penalties under the Companies Act.
    • The Companies Compliance Facilitation Scheme, 2026 closed on 15 September 2026, so pending filings now carry the full additional fee.

    AOC-4 MGT-7 due date for FY 2025-26

    The due dates are linked to the date on which the AGM is actually held, not to a fixed calendar date. The table below assumes the AGM was held on the last permitted date.

    FormWhat it containsTime limitDue date if AGM on 30 Sep 2026
    AOC-4 / AOC-4 XBRL / AOC-4 CFSAudited financial statements and board’s report30 days from AGM30 October 2026
    MGT-7Annual return (other companies)60 days from AGM29 November 2026
    MGT-7AAnnual return for small companies and OPCs60 days from AGM29 November 2026
    AOC-4 (OPC)Financial statements of a One Person Company180 days from year end27 September 2026

    If your AGM was held earlier, say on 15 September, the dates move earlier too. If the Registrar granted an extension for holding the AGM, the filing periods run from the date the adjourned or extended meeting is actually held. Where an AGM could not be held at all, the forms are still to be filed within the same periods counted from the last date on which the AGM should have been held.

    Which form applies to your company

    • AOC-4: the standard form for most companies filing standalone financial statements.
    • AOC-4 XBRL: for listed companies and their Indian subsidiaries, companies with paid-up capital of ₹5 crore or more, turnover of ₹100 crore or more, and other classes specified in the rules.
    • AOC-4 CFS: for companies that must prepare consolidated financial statements, filed in addition to the standalone form.
    • MGT-7A: the abridged annual return for small companies and One Person Companies.
    • MGT-7: for all other companies, and it may need certification by a practising company secretary for larger companies.

    The revised small company definition

    From 1 December 2025, a private company is a small company if its paid-up capital does not exceed ₹10 crore and its turnover does not exceed ₹100 crore, with both conditions met. The earlier limits were ₹4 crore and ₹40 crore. Many companies that filed MGT-7 last year may now be eligible for the simpler MGT-7A, and for other small-company relaxations. Check your status against the latest audited figures before choosing the form.

    Additional fees and penalties for delay

    Late filing has two separate consequences.

    Additional fee. When a form is filed after its due date, the MCA system charges an additional fee of ₹100 for each day of delay, on top of the normal filing fee. There is no ceiling, so a form filed a year late costs more than ₹36,000 in additional fee alone, and each form is counted separately.

    Penalties under the Companies Act. Independently of the fee, the Registrar may levy penalties:

    • Section 137 (financial statements): on the company, ₹10,000 plus ₹100 per day of continuing default, up to ₹2 lakh; on the managing director, CFO or other officer in default, ₹10,000 plus ₹100 per day, up to ₹50,000.
    • Section 92 (annual return): on the company and every officer in default, ₹10,000 plus ₹100 per day, subject to maximums of ₹2 lakh for the company and ₹50,000 for each officer.

    Small companies, One Person Companies and eligible start-ups benefit from section 446B, under which penalties are limited to one-half of the normal amount, subject to lower caps. Continued non-filing for several years can also lead to disqualification of directors and, in some cases, action to strike the company off the register.

    What about the facilitation scheme?

    The Companies Compliance Facilitation Scheme, 2026 allowed defaulting companies to file pending documents by paying a reduced additional fee. After extensions, it closed on 15 September 2026. Pending filings now attract the full additional fee, so it is sensible to clear any backlog without further delay.

    A practical filing checklist

    1. Audited financial statements signed by the board and the auditor, with the auditor’s report and, where applicable, the CARO report.
    2. Board’s report with all required annexures, signed as authorised by the board.
    3. AGM details, including the date of the meeting and any extension, entered consistently in both AOC-4 and MGT-7.
    4. Shareholding pattern as at the year end, with changes during the year and a list of shareholders and debentureholders.
    5. Details of board and committee meetings and attendance, and of directors and key managerial personnel.
    6. Remuneration details of directors and KMP, where required in the form.
    7. Valid DSCs of the signatories and professionals certifying the forms, checked for expiry in advance.
    8. Company master data on the MCA portal reviewed, so pre-filled fields such as class of company and address are correct.

    A frequent cause of rejections is a mismatch between the AGM date or financial figures reported in AOC-4 and those in MGT-7. Preparing both from the same source file avoids this.

    Linking ROC filings with your tax compliance

    The audited accounts filed in AOC-4 are the same accounts used for income tax. If your company also needs a tax audit, aligning both timelines saves effort, and our guide on the tax audit for FY 2025-26 explains the revised tax audit dates. For partnerships structured as LLPs, see our upcoming guide to LLP Form 8 and Form 11. You can view your company’s filing status on the MCA portal.

    Frequently asked questions

    What is the AOC-4 due date for FY 2025-26?

    AOC-4 is due within 30 days of the AGM. If the AGM was held on 30 September 2026, the due date is 30 October 2026. For a One Person Company, it is 180 days from the year end, that is 27 September 2026.

    What is the MGT-7 due date for FY 2025-26?

    MGT-7 or MGT-7A is due within 60 days of the AGM. For an AGM held on 30 September 2026, that is 29 November 2026.

    What is the late fee for AOC-4 and MGT-7?

    An additional fee of ₹100 per day of delay applies to each form, with no maximum. Penalties under sections 137 and 92 of the Companies Act may apply separately.

    Can my company file MGT-7A instead of MGT-7?

    Yes, if it is a small company or a One Person Company. From 1 December 2025, a private company with paid-up capital up to ₹10 crore and turnover up to ₹100 crore qualifies as a small company.

    If you would like help preparing and filing your AOC-4 and MGT-7 on time, we would be glad to assist you.

    This article is general information based on the law as of September 2026, and is not legal or tax advice. Please check the facts of your own case with a professional before acting.