Tag: ODI

  • Overseas Direct Investment (ODI) from India: Rules for Companies and Individuals

    Overseas Direct Investment (ODI) from India: Rules for Companies and Individuals

    Indian businesses and founders are increasingly investing abroad, whether to set up a sales subsidiary in Dubai, acquire a small company in the UK or form a US entity to serve American clients. The ODI rules overseas investment framework under FEMA sets out who can invest, how much, in what and with what reporting. Getting the structure right at the start avoids approvals and compounding later.

    The current framework came into force in August 2022 through the Foreign Exchange Management (Overseas Investment) Rules, 2022, the related Regulations and RBI’s Master Direction. This guide summarises the main rules for Indian companies and resident individuals.

    Key takeaways

    • ODI means investment in unlisted foreign equity, or 10% or more of a listed company’s equity, or investment with control; other investments are overseas portfolio investment (OPI).
    • An Indian entity can make financial commitments up to 400% of its net worth; commitments above USD 1 billion in a financial year need RBI approval.
    • Resident individuals invest within the LRS limit of USD 250,000 a year, only in operating entities outside financial services, and cannot control an entity with its own subsidiaries.
    • Investments in real estate business, gambling and INR-linked financial products are prohibited.
    • Reporting runs through the authorised dealer bank: Form ODI before or at the time of investment, and an Annual Performance Report by 31 December each year.

    ODI or OPI: the first question

    InvestmentClassification
    Any equity in an unlisted foreign companyODI
    Less than 10% of a listed foreign company, without controlOPI
    10% or more of a listed foreign company, or any stake with controlODI
    Debt, guarantees or pledges for a foreign entity in which ODI is madePart of financial commitment

    ‘Control’ includes the right to appoint a majority of directors or to control management or policy decisions, including through shareholding of 10% or more of voting rights. Once an investment is classified as ODI, it remains so even if the stake later reduces, unless it is fully disinvested.

    Rules for Indian companies and LLPs

    Financial commitment limit

    An Indian entity’s total financial commitment, covering equity, debt, guarantees and pledges, cannot exceed 400% of its net worth as per the last audited balance sheet. Some commitments are counted at a lower value, and some forms of guarantee are included only in part, so the calculation should be prepared carefully.

    Where the investment can go

    • A foreign entity engaged in a bona fide business activity, directly or through step-down subsidiaries.
    • Investment in a foreign entity in the financial services sector is allowed subject to extra conditions, such as the Indian entity itself being in financial services and meeting profitability and regulatory tests.
    • Investment in start-ups abroad is allowed only from the Indian entity’s internal accruals.

    Round-tripping safeguards

    An Indian entity cannot make ODI in a foreign entity that has invested, or invests, in India if the structure results in more than two layers of subsidiaries, subject to specified exceptions. Structures such as an Indian parent owning a foreign company that in turn owns an Indian company need careful review.

    Worked example

    A Pune software company has net worth of ₹12 crore as per its last audited balance sheet. Its ODI limit is 400% of that, or ₹48 crore. It plans to invest USD 2 million (roughly ₹17 to 18 crore) in equity of a new Singapore subsidiary and give a corporate guarantee of USD 1 million for the subsidiary’s bank line. Both count toward the limit, which is comfortably met, so the investment can proceed under the automatic route with Form ODI filed through its AD bank.

    Rules for resident individuals

    • Investment is made under the Liberalised Remittance Scheme, within USD 250,000 per financial year across all LRS remittances.
    • ODI is permitted only in an operating foreign entity, not engaged in financial services.
    • An individual cannot make ODI with control in a foreign entity that has a subsidiary or step-down subsidiary.
    • Shares can also be acquired by gift, inheritance, ESOPs or sweat equity, subject to conditions.
    • Remittances under LRS can attract TCS above the threshold at the time of remittance, which can be adjusted against income-tax.

    If you are setting up a US entity as an individual, our guide to compliance for a US LLC owned by an Indian resident covers both sides of the border.

    Prohibited investments

    ODI is not allowed in a foreign entity engaged in:

    • Real estate activity, meaning buying and selling of real estate or trading in transferable development rights (building townships or infrastructure is permitted).
    • Gambling in any form.
    • Dealing in financial products linked to the Indian rupee without RBI approval.

    Investments in certain jurisdictions, such as Pakistan, need government approval, and investment in countries identified as non-cooperative by FATF is restricted.

    Reporting and ongoing compliance

    EventReportTimeline
    Financial commitmentForm ODI through the AD bankBefore or at the time of the investment
    Evidence of investmentShare certificate or equivalentWithin six months
    Annual performanceAnnual Performance Report (APR)By 31 December each year, based on the foreign entity’s accounts
    Restructuring or disinvestmentForm ODI / FC as applicableWithin 30 days
    Portfolio investments by listed Indian companiesForm OPIHalf-yearly
    Foreign liabilities and assetsFLA return to RBIBy 15 July each year

    Delays can generally be regularised by paying a late submission fee, under a formula similar to the one we explain in our guide to FDI reporting through FC-GPR and FC-TRS. An Indian entity with reporting delays cannot make further financial commitments until the delay is regularised.

    Practical checklist before you invest abroad

    1. Decide the investor: the Indian company, an LLP or the promoter individually.
    2. Confirm ODI vs OPI and check the sector and jurisdiction restrictions.
    3. Calculate the financial commitment limit from the latest audited net worth.
    4. Obtain a valuation where the rules require it for acquisitions or transfers.
    5. Pass board (and where needed, shareholder) resolutions.
    6. Share documents with the AD bank, obtain the UIN and remit.
    7. Calendar the share certificate, APR and FLA deadlines.
    8. Plan the tax side, including transfer pricing for intra-group transactions and disclosure of foreign assets.

    Frequently asked questions

    What is the limit for an Indian company to invest abroad?

    Up to 400% of its net worth as per the last audited balance sheet, with commitments above USD 1 billion in a financial year needing RBI approval.

    Can a resident individual set up a company abroad?

    Yes, within the LRS limit and in an operating business outside financial services. The individual cannot control an entity that has its own subsidiaries.

    What is the due date for the Annual Performance Report?

    The APR is due by 31 December each year for every foreign entity in which ODI has been made, based on its latest accounts.

    Is RBI approval needed for most ODI?

    No. Most investments fall under the automatic route through the AD bank. Approval is needed only in specified cases, such as exceeding the limits or investing in restricted sectors or jurisdictions.

    If you are planning an overseas investment from India, our team would be glad to help you structure it and manage the FEMA reporting.

    This article is general information based on the law as of September 2026, and is not legal or tax advice. Please check the facts of your own case with a professional before acting.
  • US LLC Owned by an Indian Resident: Tax Filings and Compliance Basics

    US LLC Owned by an Indian Resident: Tax Filings and Compliance Basics

    A US LLC owned by an Indian resident is a popular structure for founders selling software, services or products to American customers. It is quick to form, gives access to US payment gateways and marketplaces, and signals credibility to US buyers. What is sometimes overlooked is that the structure carries filing duties in both countries, even in a year with little or no activity.

    The compliance is manageable once it is mapped out clearly. This guide covers the US federal and state filings, the Indian foreign exchange rules for making the investment, and the Indian income-tax reporting that follows, with a simple annual calendar at the end.

    Key takeaways

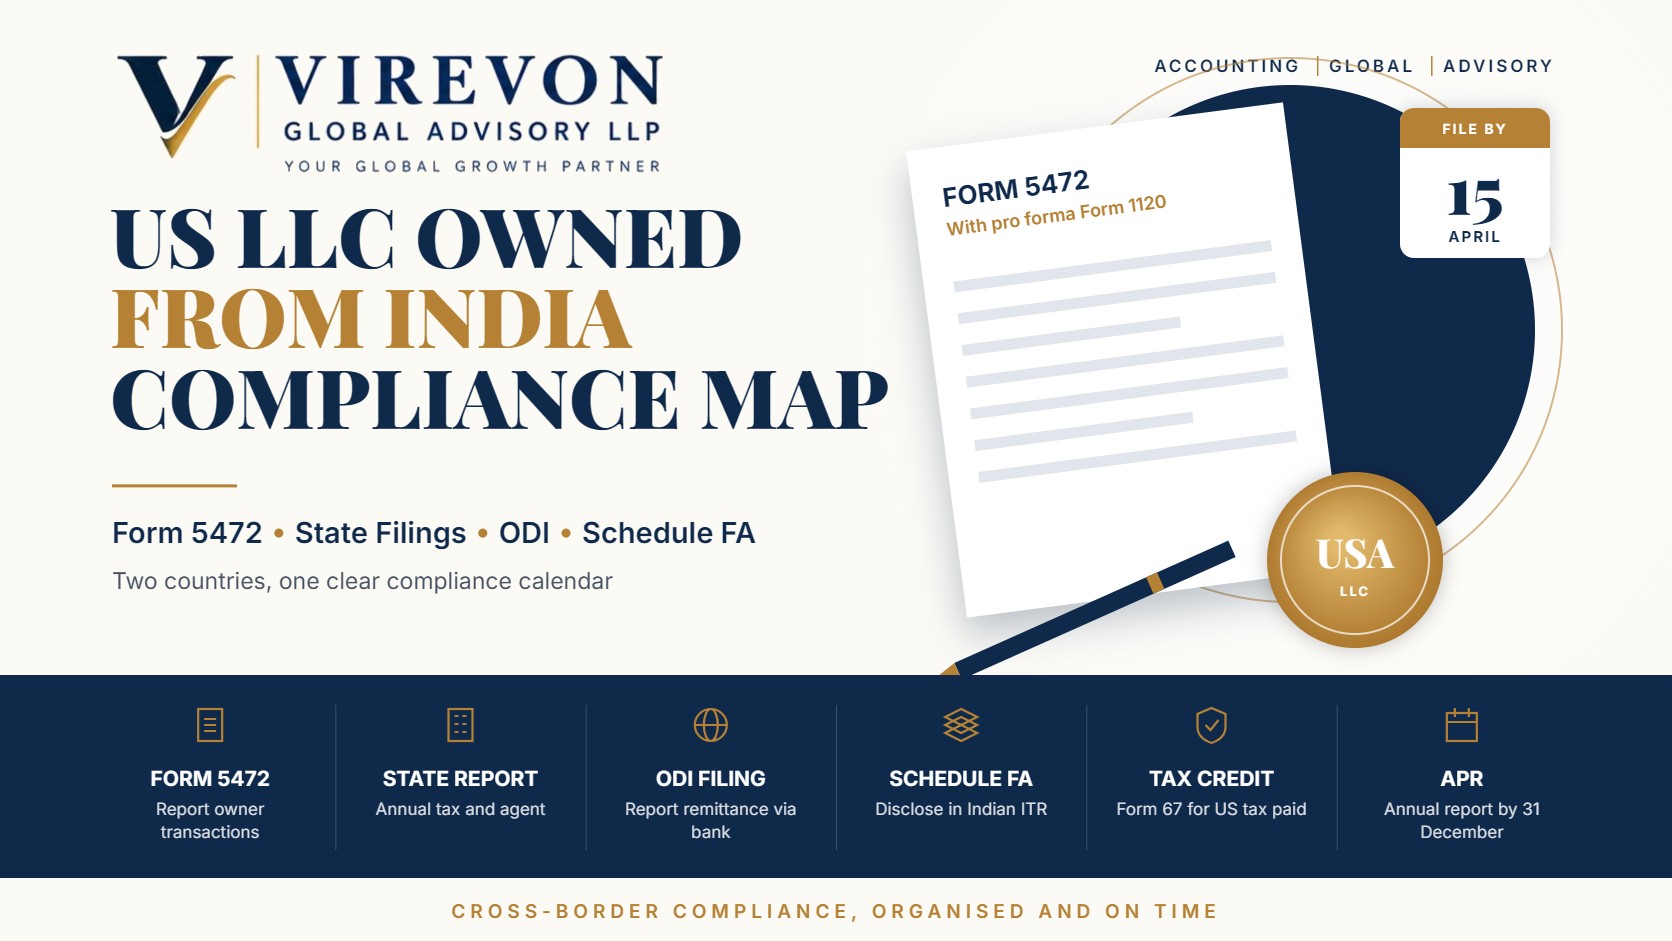
    • A single-member LLC owned by a non-US person is a disregarded entity for US income tax, but it must still file Form 5472 with a pro forma Form 1120 every year; the penalty for missing it starts at $25,000.
    • A multi-member LLC is treated as a partnership by default and files Form 1065, with additional withholding rules where it earns US-connected income.
    • States require annual reports or franchise taxes and a registered agent; Delaware’s LLC annual tax is $300, due 1 June.
    • On the Indian side, investing in a US LLC is an overseas direct investment under FEMA and must be reported through your bank.
    • The LLC interest must be disclosed in Schedule FA of your Indian income-tax return, and foreign tax credit, if claimed, needs Form 67.

    US federal filings for a US LLC owned by an Indian resident

    Single-member LLC

    By default, the IRS disregards a single-member LLC for income-tax purposes. For a foreign owner, US regulations nevertheless treat it as a corporation for one purpose: reporting transactions with its foreign owner. That creates an annual obligation:

    • Form 5472 reporting all transactions between the LLC and its owner or related parties, including money contributed to set up the LLC, capital introduced, loans and distributions.
    • A pro forma Form 1120 that carries only basic details, marked “Foreign-owned U.S. DE”.
    • Due by the corporate return due date (15 April for calendar-year entities), extendable with Form 7004.

    The penalty for not filing is $25,000, with further penalties if the failure continues after IRS notice. This is the single most important deadline for foreign-owned LLCs.

    Whether the owner also has to file a US income-tax return (Form 1040-NR) depends on whether the LLC is engaged in a US trade or business. An Indian resident providing services from India through the LLC, with no US office, staff or dependent agent, is often not in that position, but facts vary and should be reviewed each year.

    Multi-member LLC

    An LLC with two or more members is taxed as a partnership unless it elects otherwise. It files Form 1065 and issues Schedule K-1 to each member. If the partnership has income effectively connected with a US business, it must withhold tax on the foreign partners’ shares and file related forms. An LLC can also elect to be taxed as a corporation, which changes the filings entirely.

    State and other US requirements

    ItemWhat is neededTypical timing
    Registered agentA US address in the formation state for legal noticesContinuous, renewed annually
    Delaware LLC annual tax$300 flat taxBy 1 June each year
    Wyoming annual reportReport with a licence tax, minimum $60First day of the anniversary month
    Other statesAnnual or biennial reports, varying feesAs per the state calendar
    Sales taxRegistration where economic nexus is triggeredMonthly, quarterly or annual

    If you sell goods online, read our guide on US sales tax nexus for online sellers, as sales tax is separate from federal income tax.

    Beneficial ownership (BOI) reporting to FinCEN was narrowed by an interim rule in March 2025 that exempted companies formed in the United States. Keep an eye on any final rule, but most US-formed LLCs currently have no BOI filing.

    The Indian side: FEMA and overseas investment

    For an Indian resident individual, putting money into a US LLC is an overseas direct investment (ODI) under the Foreign Exchange Management (Overseas Investment) Rules and Regulations, 2022. The key points are:

    1. The investment is made under the Liberalised Remittance Scheme limit of USD 250,000 per financial year.
    2. The foreign entity must be engaged in a bona fide business activity. Resident individuals cannot make ODI in an entity engaged in financial services activity.
    3. Individuals are restricted from making ODI in a foreign entity that has its own subsidiary or step-down subsidiary where the individual has control.
    4. The remittance is made through an authorised dealer bank, which reports it in the prescribed ODI form.
    5. An Annual Performance Report is generally required for each overseas entity by 31 December, based on its financial statements.

    Delays in reporting can be regularised by paying a late submission fee, so it is worth getting this right from the first remittance.

    The Indian side: income-tax reporting

    As an Indian resident, you are taxed in India on worldwide income. Practical points include:

    • Schedule FA: disclose your interest in the LLC, the initial and peak investment, and income from it in the foreign assets schedule of your return. Non-disclosure can attract penalty under the black money law.
    • Foreign income: report dividends, distributions or other income from the LLC in the appropriate schedule. How LLC profits are taxed in India, on distribution or otherwise, depends on the structure and facts; take advice before finalising the approach.
    • Foreign tax credit: if US tax has been paid, credit may be available under the India-US tax treaty, subject to filing Form 67 within the prescribed time.
    • Control from India: where key management decisions are made in India, questions of residence and permanent establishment can arise; keep board and member decisions properly documented.

    Annual compliance calendar

    • January to March: close the LLC’s books for the calendar year and reconcile bank and payment gateway accounts.
    • By 15 April: file Form 5472 with pro forma 1120 (or Form 1065 for multi-member LLCs), or file Form 7004 for an extension.
    • By 1 June: pay the Delaware annual tax, if applicable, and check other state reports.
    • July to September: file your Indian return with Schedule FA and Form 67, where relevant.
    • By 31 December: submit the Annual Performance Report through your bank.

    Good bookkeeping makes every item on this list easier. Our note on outsourced bookkeeping for US small businesses explains a cost-effective setup.

    Frequently asked questions

    Does my LLC need to file if it had no income?

    Yes, a foreign-owned single-member LLC generally files Form 5472 with a pro forma 1120 every year, and the formation and capital contribution are themselves reportable transactions.

    Can an Indian resident own 100 percent of a US LLC?

    Yes, subject to the FEMA overseas investment rules, including the LRS limit and the restriction on financial services entities.

    Do I need a US tax ID?

    The LLC needs an EIN to file Form 5472 and open US bank accounts. An individual ITIN is needed only in specific cases, such as filing a personal US return.

    Is Form 5472 filed electronically?

    It can be filed with a pro forma 1120 by mail or fax as per the IRS instructions for foreign-owned disregarded entities.

    If you own or plan to set up a US LLC from India and would like help mapping the US and Indian compliance, our cross-border team would be happy to help.

    This article is general information based on the law as of September 2026, and is not legal or tax advice. Please check the facts of your own case with a professional before acting.