Tag: ITR filing

  • Belated and Revised Income Tax Returns: Deadlines, Fees and Practical Tips

    Belated and Revised Income Tax Returns: Deadlines, Fees and Practical Tips

    Missed the ITR due date for FY 2025-26, or spotted a mistake after filing? The Income-tax law gives you two remedies — the belated return and the revised return. Understanding the belated return revised return rules helps you act in time, keep costs low and avoid losing valuable benefits.

    Returns for FY 2025-26 (assessment year 2026-27) are still governed by the Income-tax Act, 1961, even though the Income-tax Act, 2025 came into force on 1 April 2026. This guide covers the key dates, fees, the benefits you may lose by filing late, and practical tips for both situations.

    Key takeaways

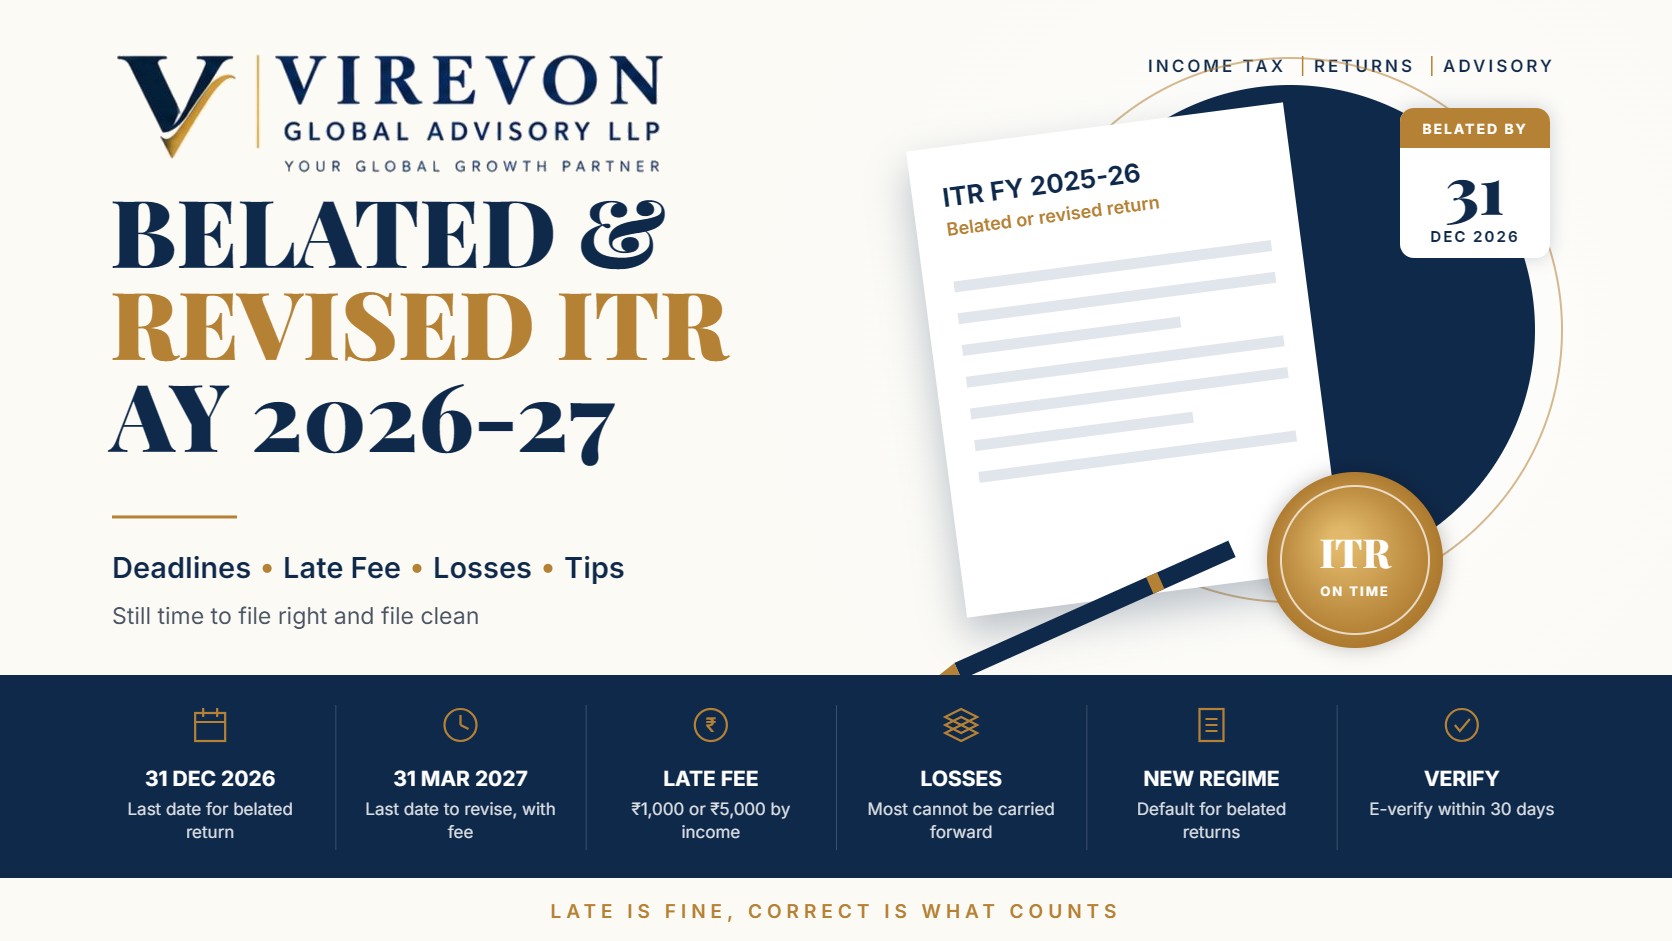
    • A belated return for FY 2025-26 can be filed up to 31 December 2026, or before assessment is completed, whichever is earlier.
    • A revised return can be filed up to 31 March 2027, or before assessment is completed, whichever is earlier.
    • A late fee of up to ₹5,000 applies to belated returns (₹1,000 where total income does not exceed ₹5 lakh), along with interest on unpaid tax.
    • From 2026, a revised return filed after 31 December attracts a separate fee of ₹1,000 or ₹5,000.
    • Business and capital losses cannot be carried forward in a belated return, and the old tax regime is generally not available.

    Belated return vs revised return at a glance

    PointBelated return (s. 139(4))Revised return (s. 139(5))
    PurposeFiling after the original due dateCorrecting a return already filed
    Last date for FY 2025-2631 December 202631 March 2027
    FeeUp to ₹5,000 under section 234FNil up to 31 Dec 2026; ₹1,000 or ₹5,000 after that under section 234I
    InterestSection 234A on unpaid taxAs applicable to the corrected tax
    Can it be revised?Yes, within the revised return time limitYes, more than once, within the time limit
    LossesMost losses cannot be carried forwardSame as the original return

    Original due dates for FY 2025-26

    For context, the original due dates for AY 2026-27 were:

    • 31 July 2026 — individuals and HUFs filing ITR-1 or ITR-2 without a tax audit.
    • 31 August 2026 — ITR-3 and ITR-4 cases not requiring a tax audit.
    • 31 October 2026 — taxpayers requiring a tax audit, and partners of such firms.
    • 30 November 2026 — cases requiring a transfer pricing report.

    If you missed your due date, the belated return is your next step. Our tax audit checklist for FY 2025-26 covers the audit-linked timelines.

    What you lose by filing a belated return

    Filing late is always better than not filing, but a few benefits are lost:

    1. Carry forward of losses: business losses, speculation losses and capital losses of the year cannot be carried forward. Unabsorbed depreciation and house property loss remain available.
    2. Choice of tax regime: the new tax regime is the default. Individuals without business income can choose the old regime only in a return filed by the due date, and those with business income must have filed the option form by the due date. A belated return therefore generally follows the new regime.
    3. Certain deductions: some profit-linked deductions require the return to be filed by the due date.
    4. Interest on tax: interest under section 234A runs at 1% per month or part of a month on the unpaid tax from the due date.

    When and how to revise a return

    A revised return is the right tool when you discover an omission or a wrong statement in a return already filed — for example, a missed deduction, a wrong bank account, an unreported interest credit or an incorrect TDS claim.

    Useful points:

    • You can revise an original or belated return.
    • You can revise more than once; the latest valid revised return replaces the earlier ones.
    • The revised return must be complete in itself, not just the change.
    • Select “revised” in the filing section and quote the acknowledgement number and date of the original return.
    • E-verify within 30 days, or the return may be treated as not filed.

    If the revision window has passed and you need to report more income, the updated return (ITR-U) may help, at the cost of additional tax.

    Late fee and fee on revised return

    Section 234F (belated returns):

    • ₹5,000 where total income exceeds ₹5 lakh.
    • ₹1,000 where total income does not exceed ₹5 lakh.

    Section 234I (revised returns, inserted in 2026): a revised return filed after 31 December 2026 but by 31 March 2027 attracts a fee of ₹1,000 (income up to ₹5 lakh) or ₹5,000 (other cases). The practical message is to revise before the calendar year ends where you can.

    Any tax due must be paid with interest before filing; the return will not be complete otherwise.

    Practical tips for a smooth filing

    • Reconcile AIS, TIS and Form 26AS before filing so the return matches the department’s data.
    • Pay self-assessment tax first and enter the challan details carefully.
    • Double-check bank details and pre-validate the refund account.
    • Keep working papers for deductions and exemptions claimed.
    • Respond promptly to intimations — see our guide on section 143(1) intimations if you receive one.
    • Do not wait for the last week of December or March; portal traffic is heavy and small errors become hard to fix.

    Frequently asked questions

    Can I file a belated return after 31 December 2026?

    No. After that date, the only route to file for FY 2025-26 is an updated return (ITR-U), which carries additional tax and cannot be used to claim a refund.

    Can I claim a refund in a belated return?

    Yes. A refund can be claimed in a belated return, and interest on the refund is generally computed from the date of filing rather than from 1 April.

    Can I change from the new regime to the old regime in a revised return?

    Only if the original return was filed by the due date with the old regime available to you. A belated return generally cannot opt for the old regime, and revising it does not change that.

    Will a revised return trigger scrutiny?

    Revising a return is a normal, legitimate correction. Scrutiny depends on risk parameters, not on the fact of revision alone. Keeping clear records supports your position either way.

    If you need help filing a belated or revised return for FY 2025-26, our team is happy to guide you through it quickly and carefully.

    This article is general information based on the law as of September 2026, and is not legal or tax advice. Please check the facts of your own case with a professional before acting.
  • ITR for NRIs: Which ITR Form, What to Report and Common Mistakes

    ITR for NRIs: Which ITR Form, What to Report and Common Mistakes

    Many non-resident Indians still earn income in India: rent from a flat, interest on NRO deposits, dividends, or gains on shares and mutual funds. Filing an ITR for NRI status is often the only way to claim back excess TDS, carry forward losses and keep a clean record for future property sales or visa and loan applications.

    The process is not complicated once you know which form applies, what counts as taxable in India and where the usual errors happen. This guide covers the return for the financial year 2025-26, which is still filed under the Income-tax Act 1961.

    Key takeaways

    • Residential status decides everything; confirm it before choosing a form.
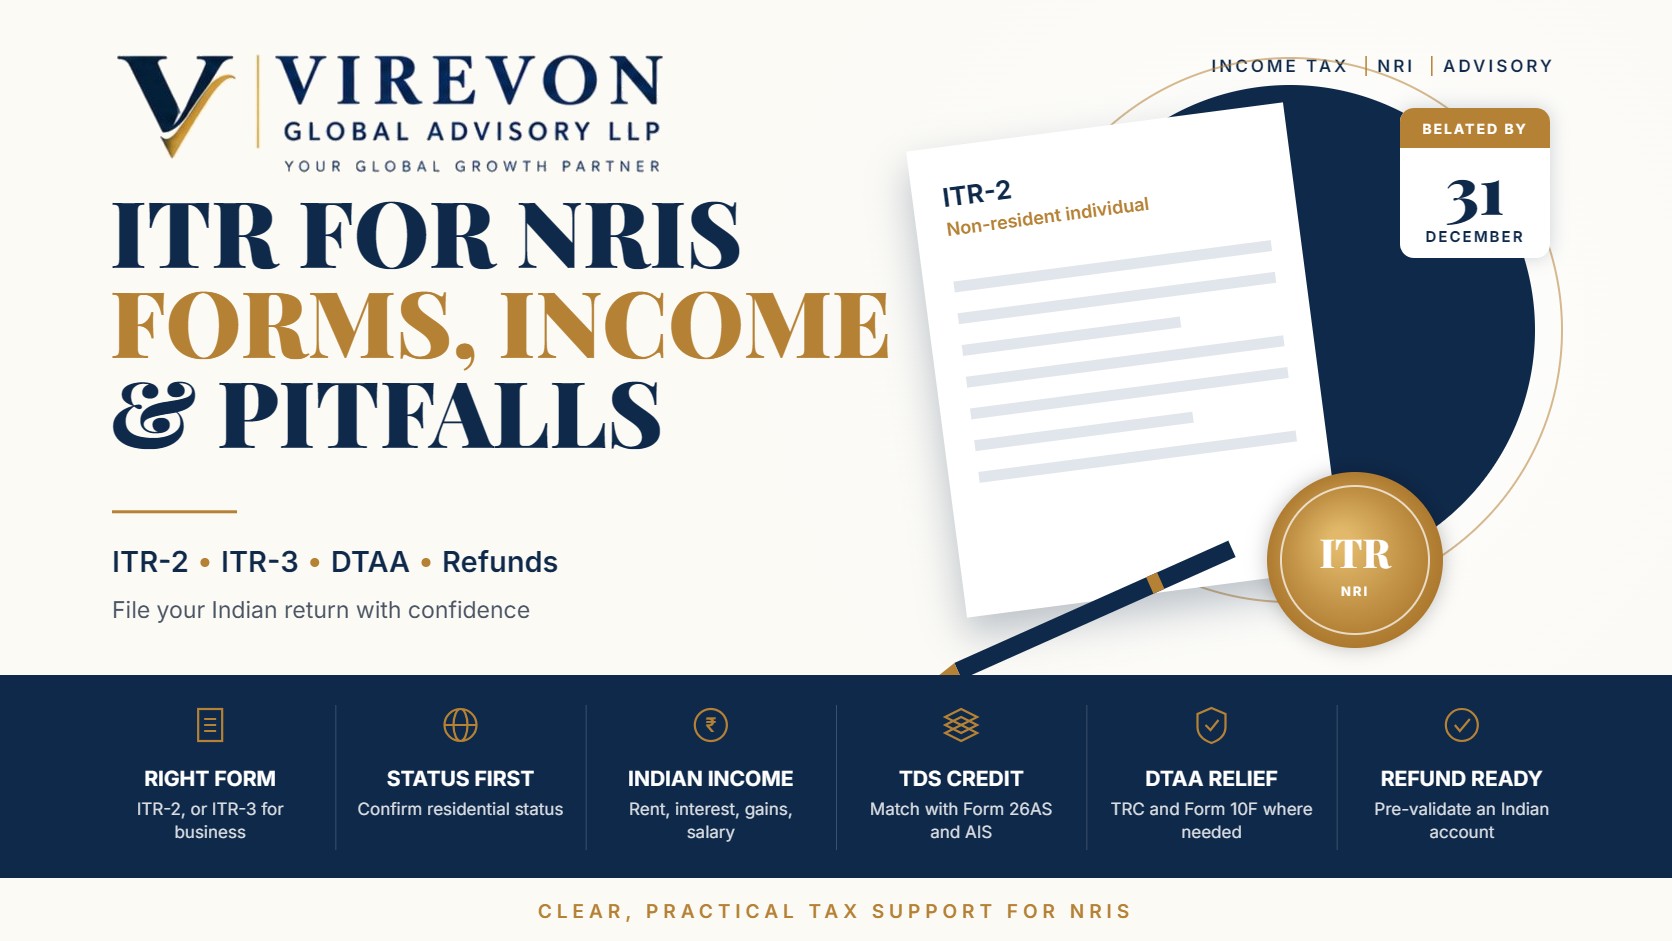
    • Most NRIs file ITR-2; ITR-3 applies only if there is business or professional income in India. ITR-1 and ITR-4 are not available to non-residents.
    • Only Indian-source income (income received, accruing or arising in India) is taxable for a non-resident; foreign income and foreign assets are not reported while non-resident.
    • The section 87A rebate is for residents only, so an NRI may owe tax even where a resident with the same income would not.
    • A belated return for FY 2025-26 can still be filed up to 31 December 2026, with a late fee.

    Step 1: Confirm your residential status

    Before anything else, work out whether you were a non-resident for FY 2025-26. The basic test looks at the number of days you were in India during the year (182 days) and, in some cases, a combination of 60 or 120 days in the year with 365 days over the previous four years. Indian citizens with Indian income above ₹15 lakh who are not taxable in any other country may be treated as deemed residents. Some returning Indians qualify as “resident but not ordinarily resident” (RNOR), which has its own reporting rules.

    Our guide on NRI residential status rules walks through each test with examples.

    Which ITR form should an NRI file?

    Your Indian incomeForm
    Salary for work in India, rent, interest, dividends, capital gainsITR-2
    Business or professional income in India (including partner remuneration)ITR-3
    Only interest income, with low total incomeUsually ITR-2 (ITR-1 is not allowed)
    Presumptive income under section 44AD or 44ADAITR-3 (ITR-4 is not allowed)

    Choosing the wrong form is one of the most common reasons for a defective return notice, so this step is worth a second look.

    What to report in an ITR for NRI

    Income from house property

    Report rent from Indian property, less municipal taxes paid, with the standard deduction of 30% and interest on a housing loan where eligible. Tenants paying rent to an NRI must deduct TDS, so check that the TDS appears in your tax credit statement.

    Interest and dividends

    Interest on NRO savings and fixed deposits is taxable. Interest on NRE accounts and FCNR deposits is generally exempt for non-residents, but should still be reviewed each year against the account type. Dividends from Indian companies are taxable and usually carry TDS.

    Capital gains

    Gains on Indian shares, mutual funds and property are taxable in India. For listed equity shares and equity-oriented funds, long-term gains above ₹1.25 lakh are taxed at 12.5% and short-term gains at 20% under the rates applying since 23 July 2024. Property sales by NRIs attract TDS at the buyer’s end; our article on TDS on NRI property sales explains how to seek a lower deduction certificate.

    Salary

    Salary for services rendered in India is taxable here even if paid abroad. Salary for work done outside India is generally not taxable in India for a non-resident.

    What you do not report

    While you are a non-resident, foreign income, foreign bank accounts and Schedule FA (foreign assets) do not need to be reported. This changes once you become resident and ordinarily resident, so plan for the year you return.

    TDS, tax credits and DTAA relief

    TDS on payments to NRIs is often deducted at higher rates under section 195, which is why many NRIs are due a refund. To claim it:

    1. Download Form 26AS and the Annual Information Statement (AIS) and match every TDS entry with your records.
    2. Report each credit in the correct schedule, including the relevant section code.
    3. If you rely on a lower treaty rate under a Double Taxation Avoidance Agreement (DTAA), keep a Tax Residency Certificate from your country of residence and file Form 10F where required. See our guide on DTAA benefit, TRC and Form 10F.
    4. Where your country taxes the same income, keep Indian tax payment evidence to claim credit there.

    Tax rates and the rebate point

    NRIs use the same slab rates as residents under the new or old regime, but they cannot claim the rebate under section 87A. Under the new regime, an NRI with ₹12 lakh of taxable Indian income would pay about ₹62,400 including cess, whereas a resident with the same income would pay nothing after the rebate. Some deductions, such as certain investment-linked ones under the old regime, are also restricted for non-residents. It is worth comparing both regimes before filing.

    Common mistakes in NRI returns

    • Filing ITR-1 out of habit from resident years.
    • Wrong residential status, particularly in the year of leaving or returning to India.
    • Missing TDS credits because the deductor used a different PAN or quarter; always reconcile with AIS.
    • Treating NRO interest as exempt in the same way as NRE interest.
    • No pre-validated Indian bank account, which delays refunds. The refund goes to an Indian account; validate it on the e-filing portal in advance.
    • Not e-verifying within the time allowed, which leaves the return incomplete.
    • Ignoring capital loss carry forward, which requires a return filed by the original due date.

    Frequently asked questions

    Is it compulsory for an NRI to file an income tax return?

    It is required if total Indian income exceeds the basic exemption limit, and it is advisable where TDS has been deducted and a refund is due or losses need to be carried forward.

    Can an NRI file ITR-1?

    No. ITR-1 is available only to resident individuals. Most NRIs use ITR-2, or ITR-3 if they have business or professional income in India.

    Is NRE account interest taxable in India?

    Interest on NRE accounts is generally exempt for a person who is non-resident, while NRO interest is taxable.

    What if I missed the original due date for FY 2025-26?

    You can still file a belated return up to 31 December 2026, with a late fee of up to ₹5,000 (₹1,000 if total income does not exceed ₹5 lakh). Some losses cannot be carried forward in a belated return.

    If you are an NRI and would like help choosing the right form, reconciling TDS or claiming a refund, we would be glad to assist.

    This article is general information based on the law as of September 2026, and is not legal or tax advice. Please check the facts of your own case with a professional before acting.