Tag: Global compliance

  • UAE VAT for Small Businesses: Registration Thresholds, Returns and Records

    UAE VAT for Small Businesses: Registration Thresholds, Returns and Records

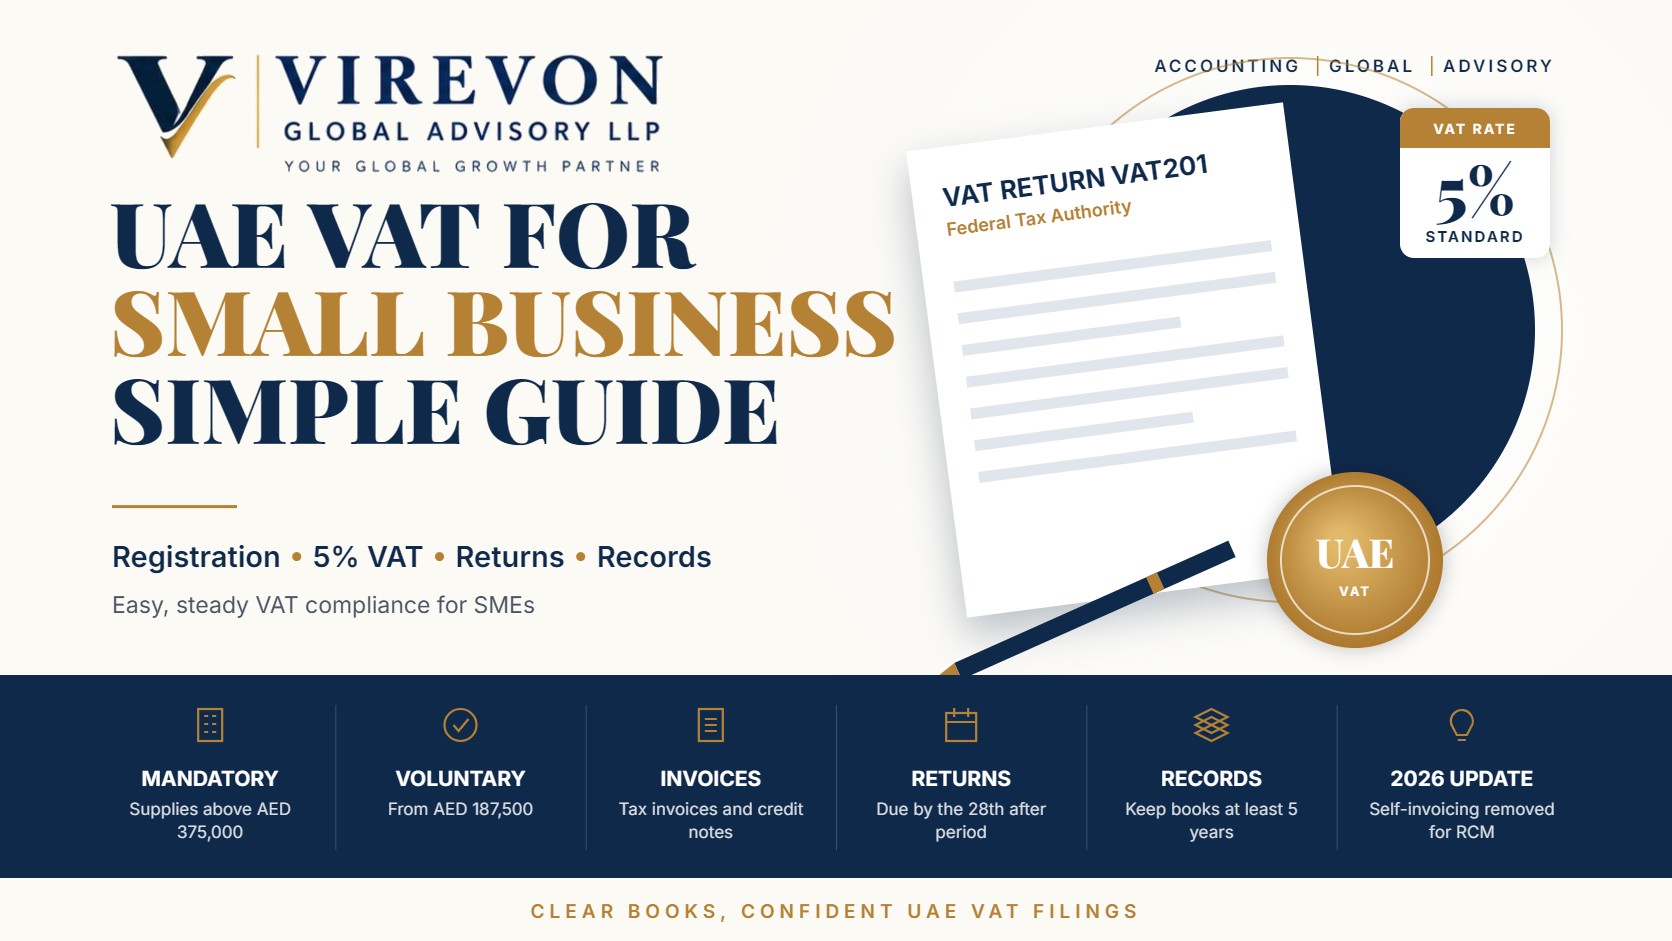
    For a small business in the UAE, VAT is usually the first tax that needs regular attention. Understanding UAE VAT for SMEs comes down to a few essentials: knowing when you must register, charging 5% correctly, filing returns on time and keeping clean records that support every figure.

    This guide covers the thresholds, the return cycle, the documents to keep and the changes that took effect from 1 January 2026. It is aimed at founders and small finance teams, including Indian owners running a UAE trading or services company.

    Key takeaways

    • The standard VAT rate is 5%, with zero-rating and exemptions for specified supplies.
    • Registration is mandatory once taxable supplies and imports exceed AED 375,000 over the previous 12 months, or are expected to in the next 30 days.
    • Voluntary registration is possible from AED 187,500 of supplies or expenses.
    • Returns are generally quarterly and due by the 28th day after the end of each tax period.
    • From 1 January 2026, self-invoicing for reverse charge imports was removed, and excess input tax must be used or claimed within five years.

    UAE VAT for SMEs: when to register

    The thresholds work on a rolling basis:

    TestThresholdResult
    Taxable supplies and imports in the past 12 monthsAbove AED 375,000Mandatory registration
    Expected taxable supplies and imports in the next 30 daysAbove AED 375,000Mandatory registration
    Taxable supplies, imports or taxable expensesAbove AED 187,500Voluntary registration allowed

    Once you cross the mandatory threshold, apply on the FTA’s EmaraTax portal within the time allowed, generally 30 days. Late registration attracts an administrative penalty, so it is worth monitoring turnover monthly as the business grows.

    Voluntary registration can be useful for start-ups with significant set-up costs, as it allows recovery of input VAT on expenses, and it signals credibility to larger customers.

    Charging VAT correctly

    Most goods and services are standard-rated at 5%. Some common exceptions:

    • Zero-rated (0%): exports of goods and services outside the GCC implementation states (subject to conditions), international transport, certain education and healthcare, and first supply of residential property within the prescribed period.
    • Exempt: certain financial services, bare land, local passenger transport and subsequent supplies of residential property.

    The difference matters: zero-rated supplies allow input VAT recovery, while exempt supplies do not.

    Tax invoices

    A tax invoice must carry the supplier’s TRN, the customer’s TRN for B2B supplies, a sequential number, the date, description, amount excluding VAT, the VAT rate and amount, and the total. Credit notes should be issued for returns, discounts after supply and corrections. From 2027, the UAE e-invoicing mandate will change how invoices are issued; our guide to the UAE e-invoicing mandate explains the phased timeline.

    Filing VAT returns

    Most small businesses file quarterly, while the FTA can assign monthly periods, usually to larger businesses. The return (VAT201) reports:

    1. Standard-rated and zero-rated supplies, by emirate for standard-rated sales.
    2. Exempt supplies and imports.
    3. Supplies subject to the reverse charge.
    4. Input VAT on expenses and imports.
    5. Net VAT payable or refundable.

    The return and payment are due by the 28th day after the end of the tax period. For a quarter ending 30 September, the deadline is 28 October.

    A simple monthly routine

    • Reconcile sales and purchase ledgers with bank statements.
    • Check that every purchase invoice claimed has a valid TRN and is in the business name.
    • Review imports and reverse charge entries.
    • Keep a list of blocked input tax items, such as most entertainment and non-business use of vehicles.

    What changed from 1 January 2026

    Federal Decree-Law No. 16 of 2025 amended the VAT law, effective 1 January 2026. The main points for SMEs:

    • No self-invoicing under reverse charge: businesses accounting for VAT on imported services or goods under the reverse charge no longer need to issue a tax invoice to themselves; supporting documents such as the supplier invoice remain important.
    • Five-year window for excess input tax: excess recoverable VAT can be carried forward or claimed for up to five years from the end of the tax period in which it arose, so older credits should be reviewed and used in time.
    • Input tax and tax evasion: input VAT can be denied where the business knew, or should have known, that a supply was connected to tax evasion. Basic supplier checks, such as verifying TRNs and keeping contracts, are now more valuable.

    Records to keep

    The FTA expects books and records that support the VAT return. Keep:

    • tax invoices, credit notes and debit notes issued and received;
    • import and export documents, including customs declarations;
    • ledgers, bank statements and reconciliations;
    • contracts for significant supplies;
    • a record of adjustments and corrections.

    Records should generally be kept for at least five years from the end of the relevant tax period, and longer for real estate. Good VAT records also make the annual corporate tax return easier; see our guide to UAE corporate tax basics.

    Common mistakes small businesses make

    • Registering late after crossing the threshold.
    • Claiming input VAT without a valid tax invoice or on blocked expenses.
    • Treating exempt supplies as zero-rated, or the other way round.
    • Missing reverse charge entries for imported services such as software subscriptions.
    • Leaving refunds or excess credits unclaimed for too long.

    Frequently asked questions

    What is the VAT registration threshold in the UAE?

    Mandatory registration applies when taxable supplies and imports exceed AED 375,000. Voluntary registration is available from AED 187,500.

    How often do small businesses file VAT returns?

    Usually quarterly. The return and payment are due by the 28th day after the end of each tax period.

    Do I still need to self-invoice for reverse charge?

    No. From 1 January 2026, businesses no longer need to issue a self-invoice for reverse charge imports, though supporting records must still be kept.

    How long should VAT records be kept?

    Generally at least five years from the end of the tax period, with longer periods for real estate records.

    If you run a small business in the UAE, our global accounting team will be glad to help you with VAT registration, bookkeeping and on-time returns.

    This article is general information based on the law as of September 2026, and is not legal or tax advice. Please check the facts of your own case with a professional before acting.
  • UAE E-Invoicing Mandate: Timeline and How Businesses Can Get Ready

    UAE E-Invoicing Mandate: Timeline and How Businesses Can Get Ready

    UAE e-invoicing is moving from plan to practice. Instead of emailing PDF invoices, businesses will exchange structured electronic invoices through accredited service providers, with invoice data reported to the Federal Tax Authority (FTA) in near real time. The rollout is phased, starting with larger businesses from 1 January 2027.

    The change is significant, but manageable with a clear plan. This guide explains the timeline, how the model works, what the penalties look like and the practical steps to get ready without disrupting your billing.

    Key takeaways

    • The framework was set out in Ministerial Decisions No. 243 and 244 of 2025, with penalties under Cabinet Decision No. 106 of 2025.
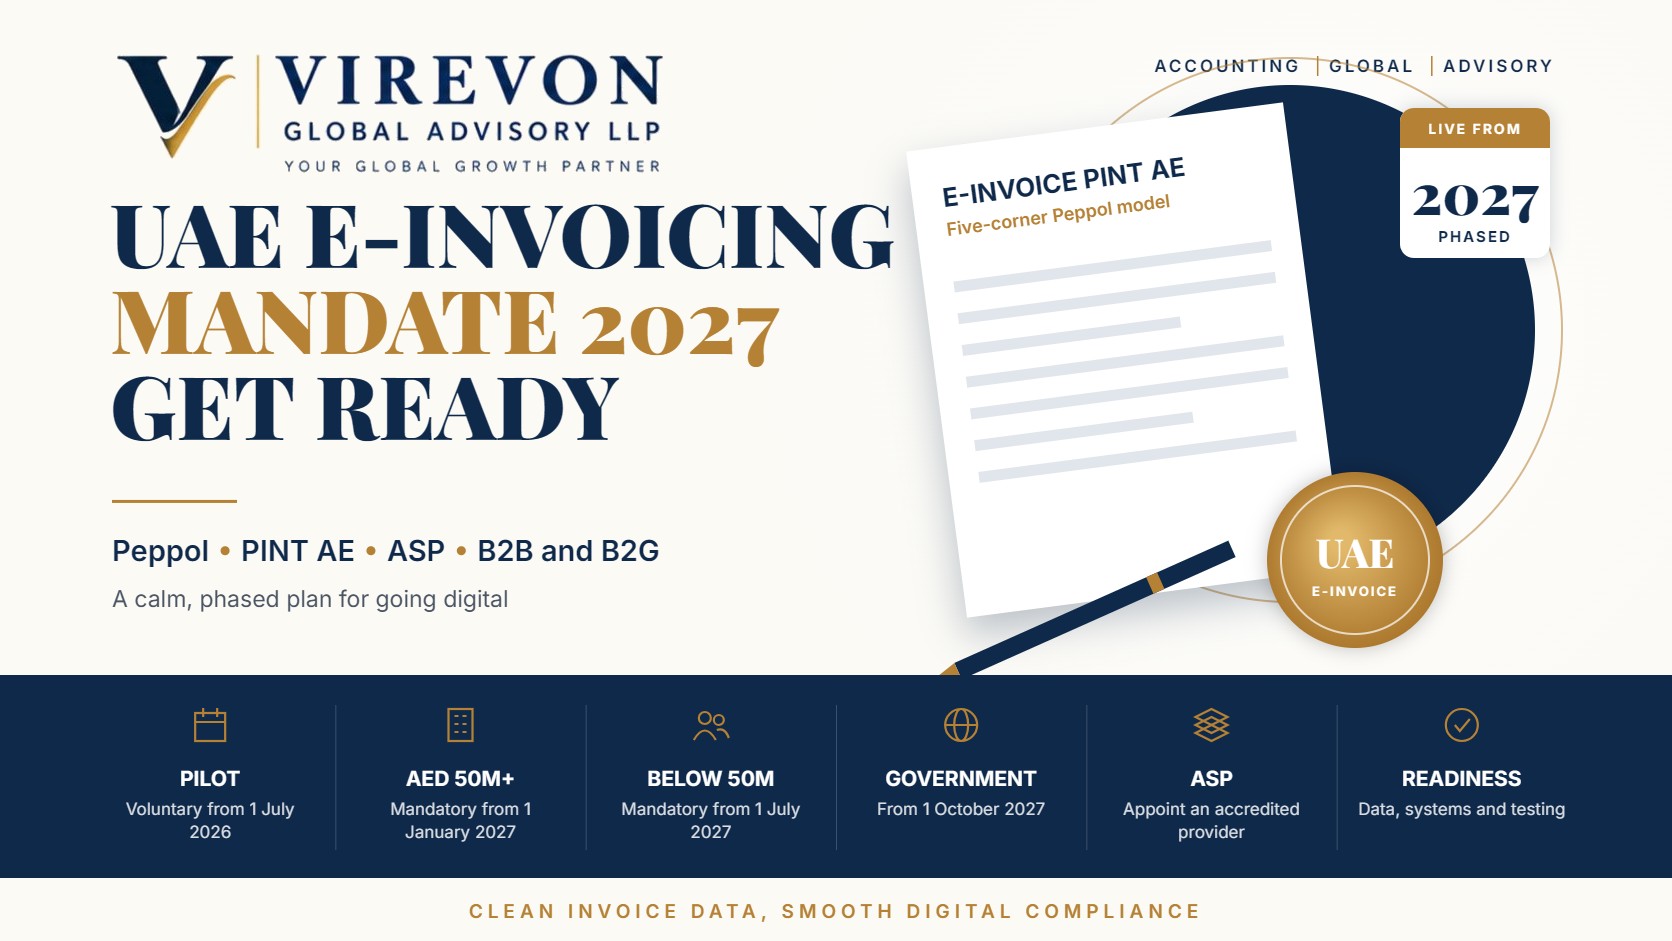
    • A voluntary pilot started on 1 July 2026; businesses with revenue of AED 50 million or more go live on 1 January 2027.
    • Businesses below AED 50 million go live on 1 July 2027, and government entities on 1 October 2027.
    • Each business must appoint an Accredited Service Provider (ASP); the deadline for the first group was extended to 30 October 2026.
    • The initial scope covers B2B and B2G transactions; B2C is outside the first phase.

    The UAE e-invoicing timeline

    GroupAppoint ASP byMandatory from
    Voluntary pilot participants—1 July 2026
    Businesses with revenue of AED 50 million or more30 October 20261 January 2027
    Businesses with revenue below AED 50 million31 March 20271 July 2027
    Government entities31 March 20271 October 2027

    Revenue for grouping purposes is based on the rules in the ministerial decision, so businesses near the AED 50 million mark should confirm their category early. Businesses can also choose to join before their mandatory date.

    How the system works: the five-corner model

    The UAE has adopted a decentralised model based on the Peppol network:

    1. Corner 1: the supplier creates the invoice in its accounting or ERP system.
    2. Corner 2: the supplier’s ASP validates the invoice and converts it to the UAE standard (PINT AE).
    3. Corner 3: the buyer’s ASP receives the invoice.
    4. Corner 4: the buyer receives it into its system.
    5. Corner 5: the FTA receives the tax data from the ASPs.

    Because both sides need an ASP, buyers as well as sellers have to be ready. A business that only purchases in scope still needs to be able to receive e-invoices.

    What counts as an e-invoice

    A PDF, scanned copy or image is not an e-invoice under this framework. The invoice must be a structured file in the prescribed format, exchanged through the ASP network. Credit notes follow the same process and are required for cancellations, reductions or corrections.

    Scope in the first phase

    • In scope: B2B and B2G supplies, whether taxable or not, subject to the exclusions in the decision.
    • Outside the initial scope: B2C transactions and certain specific categories, such as some financial and international passenger transport services, which follow separate rules.
    • VAT groups: a transition period applies for transactions within a VAT group.

    Electronic invoices must be issued within the time prescribed from the date of supply, and records must be retained in line with the UAE’s record-keeping rules.

    Penalties to be aware of

    Cabinet Decision No. 106 of 2025 sets administrative penalties, including:

    • AED 5,000 per month of delay for failing to implement the system or appoint an ASP by the deadline.
    • AED 100 per invoice or credit note not issued or transmitted electronically, capped at AED 5,000 per month.
    • AED 1,000 per day for delays in reporting a system failure or notifying the ASP of data changes.

    The amounts are modest compared with the operational disruption of a rushed implementation, which is the bigger reason to plan early.

    A practical readiness plan

    Step 1: Confirm your phase and scope

    Check annual revenue, the type of customers (B2B, B2G, B2C) and any VAT group. Map which invoices and credit notes will be in scope.

    Step 2: Clean your master data

    E-invoicing rejects poor data. Review customer TRNs, legal names, addresses, item descriptions, tax codes and units of measure. This single step prevents most validation errors.

    Step 3: Choose an ASP

    Select an FTA-accredited provider that integrates with your ERP or accounting software. Compare onboarding support, pricing per invoice, archiving and reporting features.

    Step 4: Update systems and processes

    • Configure invoice templates to capture the mandatory fields.
    • Set up integration or connectors between your software and the ASP.
    • Define how incoming e-invoices will be received, approved and booked.
    • Align credit note and cancellation workflows with the new rules.

    Step 5: Test, train and go live

    Run test invoices with key customers and suppliers, train the billing and payables team, and plan a short parallel run before the mandatory date.

    How e-invoicing links with VAT and corporate tax

    Structured invoice data gives the FTA near real-time visibility of transactions. That makes consistency between invoices, VAT returns and financial statements more important than ever. Businesses should reconcile e-invoice data with VAT returns every period and ensure the books support the corporate tax return. Our guide to UAE corporate tax basics covers the annual filing side. For official updates, refer to the Ministry of Finance e-invoicing page and FTA guidance.

    Frequently asked questions

    When does UAE e-invoicing become mandatory?

    From 1 January 2027 for businesses with revenue of AED 50 million or more, 1 July 2027 for smaller businesses and 1 October 2027 for government entities.

    Do small businesses need to do anything now?

    Yes, planning should start now. Businesses below AED 50 million must appoint an ASP by 31 March 2027 and go live by 1 July 2027.

    Is a PDF invoice sent by email an e-invoice?

    No. An e-invoice must be a structured electronic file in the prescribed format, exchanged through accredited service providers.

    Does e-invoicing apply to B2C sales?

    B2C transactions are outside the first phase. The initial mandate covers B2B and B2G transactions.

    If your UAE business is preparing for e-invoicing, our global accounting team would be glad to help you clean your data, align your books and plan a smooth go-live.

    This article is general information based on the law as of September 2026, and is not legal or tax advice. Please check the facts of your own case with a professional before acting.

  • UAE Corporate Tax Basics: Registration, 9% Rate and Filing Deadlines

    UAE Corporate Tax Basics: Registration, 9% Rate and Filing Deadlines

    UAE corporate tax has now settled into a routine for most businesses: register with the Federal Tax Authority, keep proper accounts, and file one return a year. For many small and mid-sized companies, the actual tax payable is modest, but the compliance steps still need to be done correctly and on time.

    This guide explains who must register, how the 0% and 9% bands work, what Small Business Relief and free zone status mean in practice, and the deadlines that matter. It is written for founders and finance teams, including Indian businesses with a UAE entity.

    Key takeaways

    • Corporate tax applies under Federal Decree-Law No. 47 of 2022 to financial years starting on or after 1 June 2023.
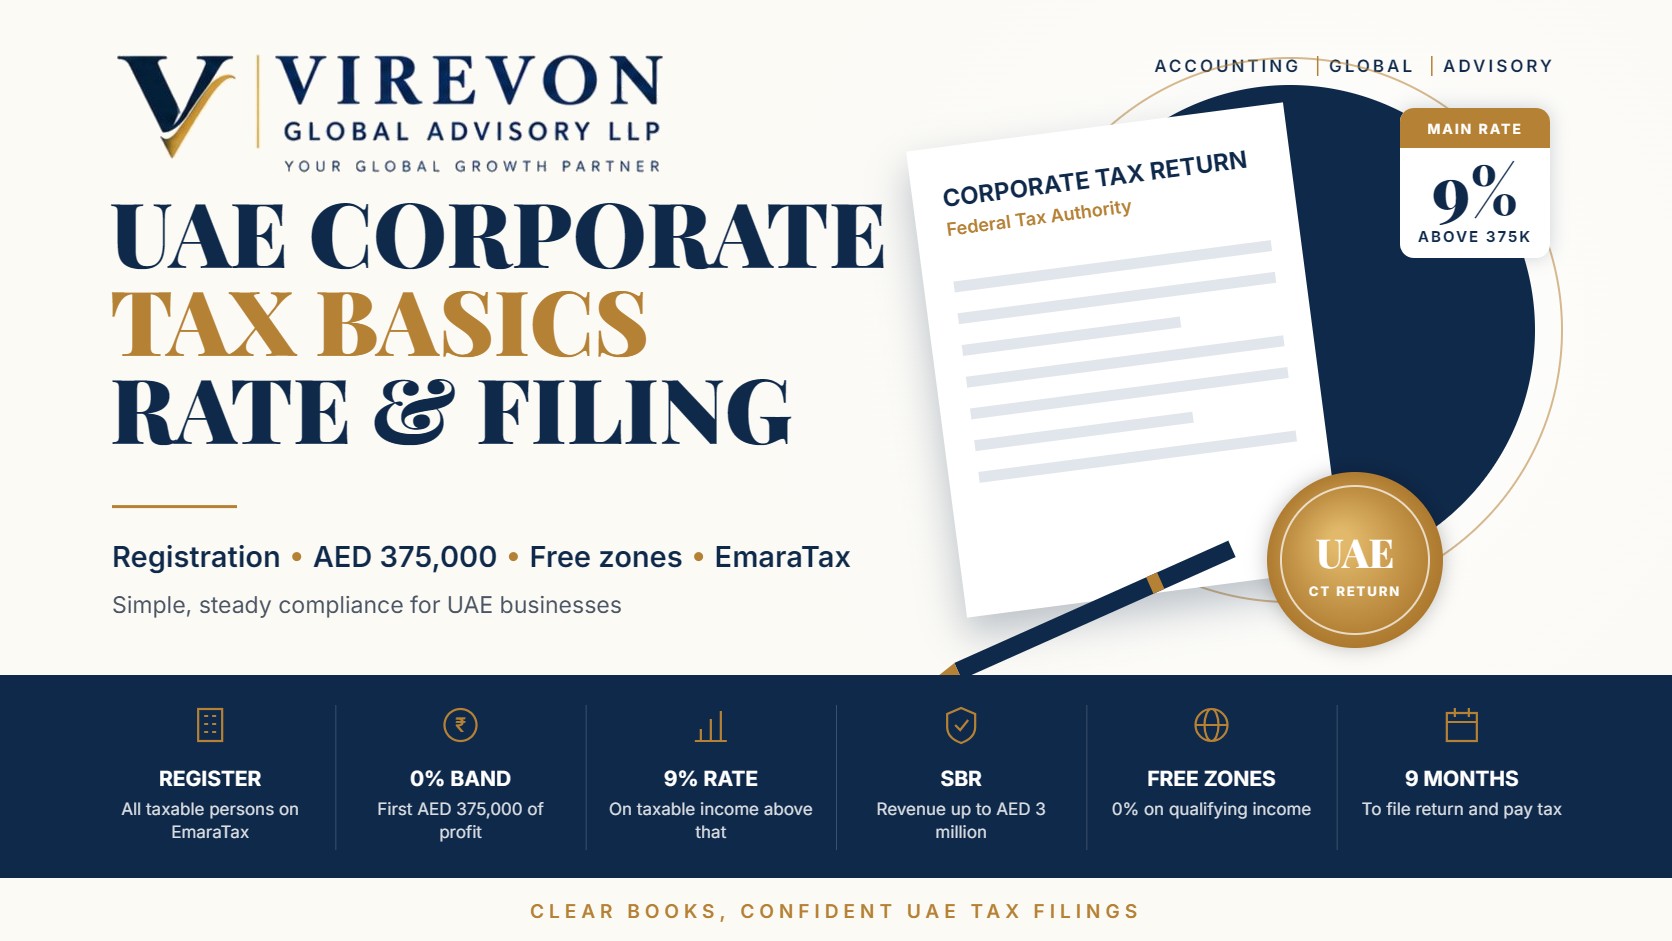
    • Taxable income up to AED 375,000 is taxed at 0%, and income above that at 9%.
    • Registration is mandatory for taxable persons, even when no tax is payable, and late registration attracts a penalty.
    • Small Business Relief can apply where revenue is AED 3 million or less, for tax periods ending on or before 31 December 2026.
    • The return and payment are due within nine months from the end of the tax period.

    Who needs to register for UAE corporate tax

    Registration is done on the FTA’s EmaraTax portal. Broadly, the following must register:

    • UAE companies and other juridical persons incorporated in the UAE, including free zone entities.
    • Foreign companies effectively managed and controlled in the UAE, or with a permanent establishment there.
    • Individuals (natural persons) carrying on business in the UAE whose turnover from that business exceeds AED 1 million in a calendar year.

    The FTA has set registration deadlines based on the entity’s licence issue date or incorporation date. New entities generally need to register within three months of incorporation. Registration results in a Tax Registration Number, which is needed for filing and for dealing with banks and counterparties.

    How the 0% and 9% rates work

    The structure is simple:

    Taxable incomeRate
    Up to AED 375,0000%
    Above AED 375,0009% on the excess

    Example: A Dubai trading company has taxable income of AED 600,000. Tax is 9% of (600,000 − 375,000) = AED 20,250.

    Taxable income starts from the accounting profit in financial statements prepared under IFRS (or IFRS for SMEs where permitted), and is then adjusted. Common adjustments include:

    • Non-deductible expenses such as fines, penalties, most entertainment costs (50% disallowed) and donations to non-qualifying bodies.
    • Limits on net interest expense, generally 30% of adjusted EBITDA, with a safe-harbour threshold for smaller amounts.
    • Exempt income such as qualifying dividends and gains on qualifying shareholdings.
    • Transfer pricing adjustments for transactions with related parties and connected persons.

    Large multinational groups with global revenue of EUR 750 million or more are also subject to a 15% Domestic Minimum Top-up Tax for financial years starting on or after 1 January 2025, but that does not affect typical SMEs.

    Small Business Relief: a useful simplification

    A resident person whose revenue is AED 3 million or less in the relevant tax period and each previous tax period can elect for Small Business Relief. If elected, the business is treated as having no taxable income for that period, and simplified reporting applies.

    Points to note:

    • The relief is available for tax periods ending on or before 31 December 2026, unless extended. Businesses should plan for regular computation from 2027 onwards.
    • It must be elected in the return; it does not apply automatically.
    • Qualifying Free Zone Persons and members of large multinational groups cannot use it.
    • Accounts still need to be maintained, and the business must still register and file.

    Free zone companies

    A free zone company that meets the conditions of a Qualifying Free Zone Person can pay 0% on qualifying income, while non-qualifying income is taxed at 9%. The main conditions are adequate substance in the free zone, earning qualifying income, not electing to be taxed at the regular rates, meeting transfer pricing rules, preparing audited financial statements and staying within the de minimis limit for non-qualifying revenue (the lower of 5% of total revenue or AED 5 million).

    Being in a free zone does not automatically mean zero tax. Businesses should map each revenue stream against the qualifying activities list every year, because failing the conditions can mean losing the benefit for the current and the following four tax periods.

    Filing and payment deadlines

    The tax period is normally the entity’s financial year. For a company following the calendar year:

    1. Tax period: 1 January to 31 December.
    2. Return and payment due: 30 September of the following year.
    3. Records: keep books and supporting documents for at least seven years.

    The return is filed on EmaraTax, and the tax is paid through the portal’s payment options. Where a business has related-party transactions above prescribed thresholds, a transfer pricing disclosure form is filed with the return. Some businesses, including those with revenue above AED 50 million and Qualifying Free Zone Persons, must also have audited financial statements.

    Late filing and late payment attract administrative penalties, so it is worth fixing an internal timeline: close the books within three months of year-end, finalise tax adjustments by month six, and file with a comfortable margin.

    Practical checklist for the year

    • Confirm your Tax Registration Number and that your EmaraTax profile is up to date.
    • Keep IFRS-compliant books with monthly reconciliations.
    • Track related-party transactions and keep simple documentation.
    • Decide early whether Small Business Relief or free zone status applies.
    • Keep an eye on the UAE’s move to e-invoicing, which will change how invoices are issued and reported. Our guide to the UAE e-invoicing mandate covers the timeline.
    • Refer to the Federal Tax Authority for the latest guides and decisions.

    Frequently asked questions

    What is the UAE corporate tax rate?

    Taxable income up to AED 375,000 is taxed at 0%, and income above that at 9%. Qualifying Free Zone Persons may pay 0% on qualifying income.

    Do I need to register if my company makes no profit?

    Yes. Registration is required for taxable persons regardless of profit, and a return must still be filed each year.

    When is the corporate tax return due?

    Within nine months from the end of the tax period. For a calendar-year company, that is 30 September of the following year.

    Is Small Business Relief automatic?

    No. It must be elected in the tax return, and it is currently available only for tax periods ending on or before 31 December 2026.

    If you run a UAE company or are setting one up, our global accounting team will be happy to help you keep IFRS books and stay on top of corporate tax filings.

    This article is general information based on the law as of September 2026, and is not legal or tax advice. Please check the facts of your own case with a professional before acting.